Search GrowthX Learning Content
Common Reasons for Delay in IRDAI Licence Approval
Obtaining approval from the Insurance Regulatory and Development Authority of India is an essential step for starting an insurance broking business. However, incorporating a company, arranging funds and submitting an application do not automatically result in approval. The applicant must establish that its ownership, management, financial position and operational arrangements meet the applicable requirements.
Delays can arise when documents are incomplete, information is inconsistent, financial records require clarification, or key appointments remain unresolved. Applications involving complex ownership structures or unfamiliar operating arrangements may also require additional examination. This article focuses on insurance broker registration, commonly called an IRDAI broker licence. Other categories, such as insurance web aggregators and corporate agents, have separate registration requirements.
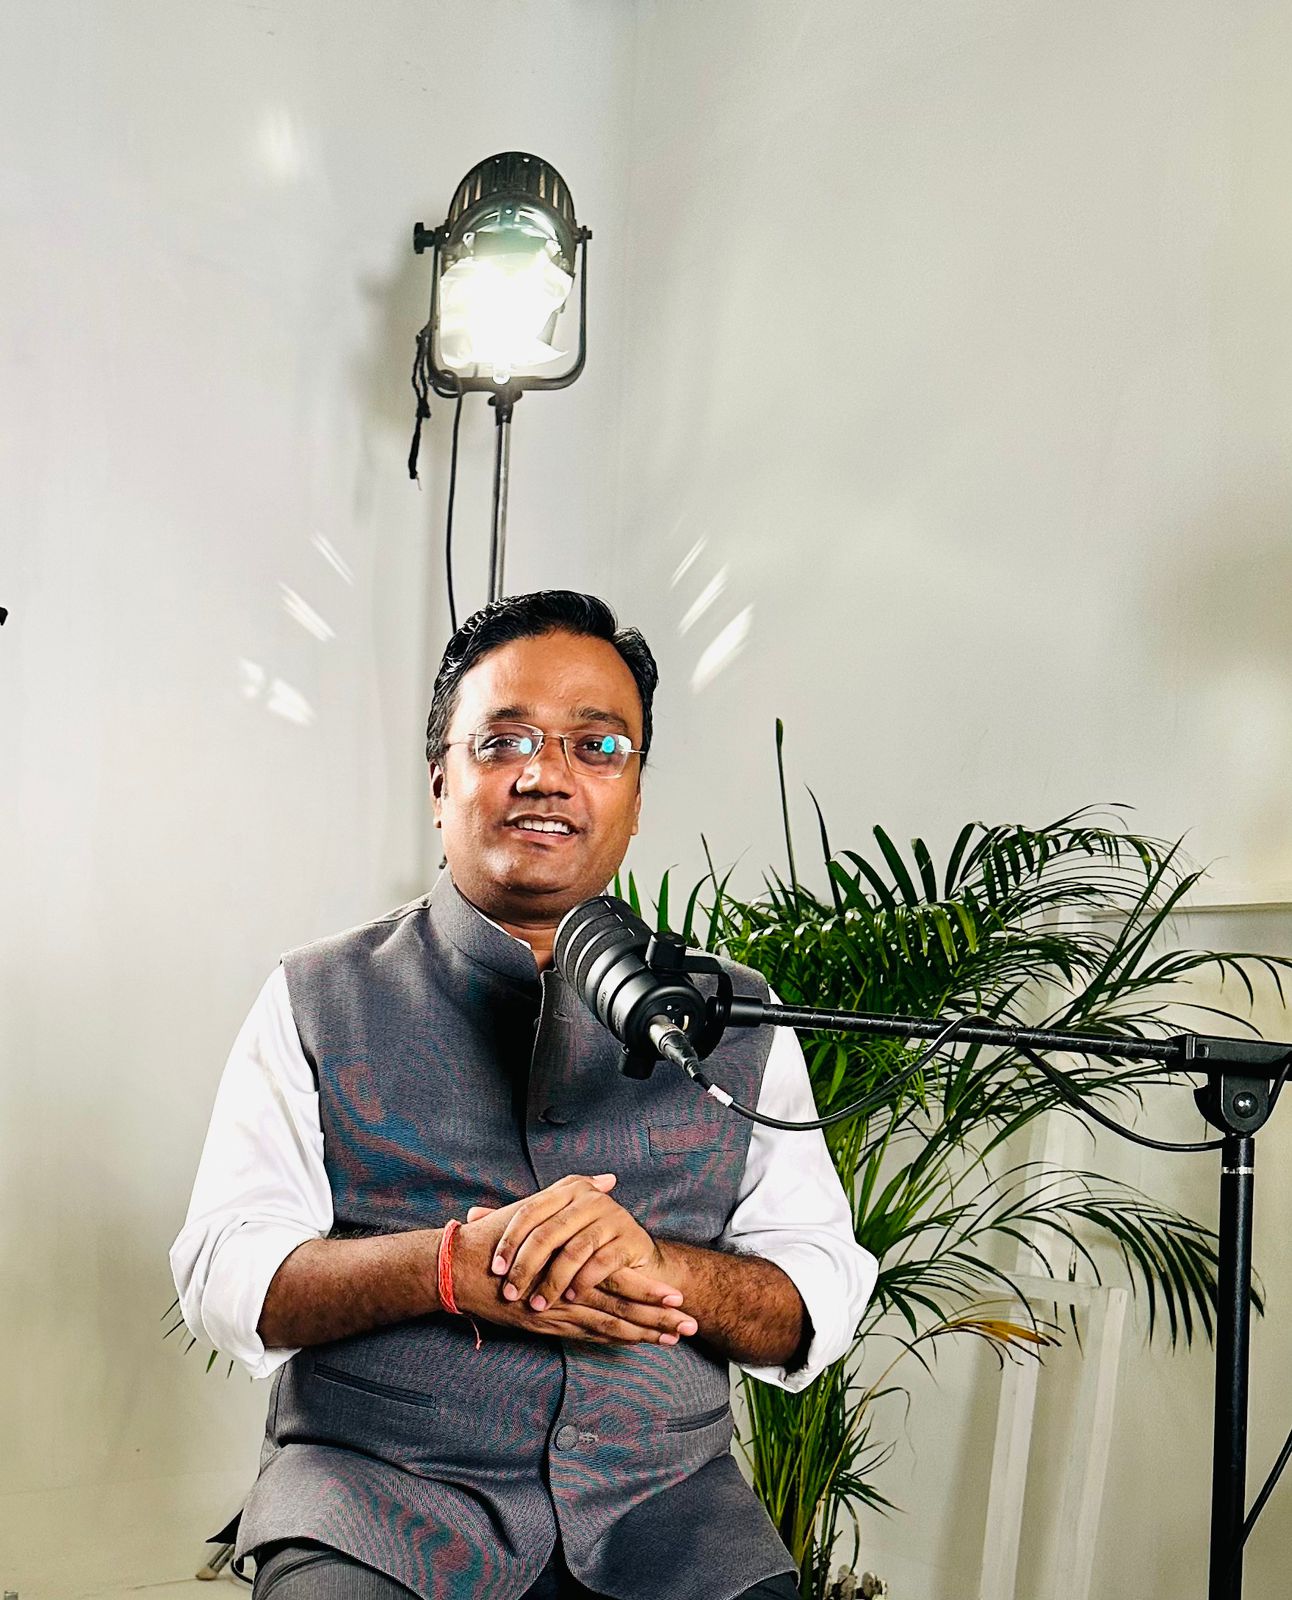
In this article, CA Manish Mishra talks about Common Reasons for Delay in IRDAI Licence Approval.
Understanding the IRDAI Approval Process
Insurance broker registration is principally governed by the IRDAI (Insurance Brokers) Regulations, 2018, read with subsequent amendments and applicable directions. The application must contain the prescribed information, supporting documents and fee payment.
IRDAI examines whether the applicant satisfies the relevant requirements. During this process, it may request clarification, seek additional documents or require the applicant and Principal Officer to attend a personal representation. Submitting an application is therefore different from establishing that it is complete and ready for approval. The reasons explained below are practical issues that can lead to additional scrutiny; they are not an official ranking of causes of delay.
Incomplete Application Documents
One avoidable cause of delay is submitting an application without all the necessary information and attachments. Missing declarations, unsigned forms, omitted financial records or incomplete personnel details can prevent the application from being assessed properly.
A document may also be technically present but incomplete. For example, a declaration might contain a signature without the signatory’s name or designation, or a financial certificate may omit the reporting date. Applicants should prepare an index and check each application requirement against the corresponding attachment. This helps identify missing information before submission and makes later clarification easier.
Inconsistent Information Across Documents
An application can require clarification even when all documents have been submitted. Differences in the applicant’s name, registered-office address, ownership percentages or management particulars can create uncertainty about which information is correct.
For example, the application may show a new office address while the lease agreement and board resolution refer to an earlier address. Similarly, a shareholding statement may differ from the ownership information used in financial disclosures. The applicant should review the entire file together. Where a difference results from a genuine change, the relevant supporting records and effective date should be explained clearly.
Incorrect Selection of Broker Category
The proposed broker category should match the activities the applicant intends to undertake. Direct insurance broking, reinsurance broking and composite broking involve different functions and preparation requirements.
Problems arise when an applicant selects one category but submits a business plan describing another. This can affect the assessment of its financial resources, staffing and professional experience. The category should be decided before the application is prepared. Constitutional documents, projections, recruitment plans and operating arrangements should consistently reflect that decision.
Constitutional Documents That Do Not Support the Proposed Business
The applicant’s constitutional documents should be consistent with its proposed insurance broking activities. If the objects or governing provisions do not adequately reflect the intended business, amendments or explanations may be necessary.
A general reference to consultancy or financial services should not automatically be assumed to satisfy the requirements applicable to insurance broking. The entity’s name should also be reviewed against the relevant naming provisions. These matters should be checked early because amendments may involve corporate approvals and filings. Addressing them only after a regulatory query can extend the preparation process.
Unclear Evidence of Capital Contribution
Financial scrutiny becomes more difficult when the applicant cannot clearly establish the capital introduced into the business. For instance, an application may state a paid-up capital figure while the supporting documents only show the authorised share capital. Alternatively, bank receipts may not clearly identify the investor or connect with the relevant allotment records.
Applicants should maintain a clear trail linking the contribution, bank receipt, corporate approval and resulting ownership position. Any professional certificate should be supported by records that explain the figures stated.
Questions About the Source of Funds
The origin and movement of investment funds may require clarification. Transfers through several accounts, unexplained third-party payments or differences between investor records and bank statements can make the funding position difficult to assess.
A useful explanation identifies the investor, amount contributed, payment date and route through which the funds reached the applicant. Submitting numerous bank statements without explaining the transactions may not resolve the issue. The documents should collectively establish a clear and consistent funding trail.
Confusion Between Capital and Net Worth
Capital and net worth are separate financial measures. An applicant may introduce capital and then incur expenses that affect its net worth before approval. Difficulties can arise when an older certificate is submitted without considering subsequent rent, salaries, professional fees and other expenditure.
Certificates prepared using different dates can also appear inconsistent if the movement is not explained. Applicants should reconcile financial certifications with the relevant accounts. Updated figures should clearly identify the reporting date and explain material differences from earlier submissions.
Incomplete Principal Officer Documentation
The Principal Officer’s qualifications, experience, appointment and suitability are important aspects of the application. Missing educational records, training evidence, examination documents or appointment records may lead to further queries.
A general statement that the individual has insurance experience may not adequately explain the nature and duration of that experience. Employment dates and responsibilities should be stated clearly. The applicant should ensure that the professional profile, prescribed particulars and supporting records agree. Any continuing employment or other role should be assessed and disclosed where required.
Unresolved Staffing Arrangements
An application may describe a substantial business without demonstrating who will perform the necessary work. CVs alone may not establish that the relevant individuals have agreed to join the applicant.
The staffing file should distinguish the Principal Officer, broker qualified persons and other employees. Their functions, qualification records and appointment status should be clear. Proposed recruitment should be presented accurately. The applicant should also ensure that staffing plans agree with the projected expenditure and operating model.
Incomplete Fit-and-Proper Disclosures
Fit-and-proper disclosures help assess the suitability of relevant individuals associated with the applicant. Missing information about business interests, directorships, professional history or relevant proceedings can require additional examination.
Each declaration should be reviewed by the person signing it. Copying an earlier declaration without checking the current facts can result in inaccurate information. Where a matter requires disclosure, the applicant should explain it clearly and provide relevant supporting records. Contradictory or incomplete disclosures are harder to assess than a properly explained position.
Complex Ownership and Group Relationships
Applications involving several corporate shareholders or multiple ownership layers may need detailed explanations of control and beneficial ownership. A list of immediate shareholders may not show who ultimately controls the applicant.
Relevant relationships with group entities may also require examination, particularly where those entities conduct insurance-related activities. An ownership chart should be supported by current corporate records. The explanation should identify the important relationships clearly and remain consistent with the application’s other disclosures.
Additional Documentation for Foreign Investment
Foreign investment may involve overseas corporate records, investment information and other documents appropriate to the ownership arrangement. Preparation can take longer where records must be obtained from several jurisdictions or where translation and authentication are required. The applicant should identify these requirements early.
It should also assess the provisions applicable specifically to insurance intermediaries. Requirements should not be copied from an insurer-registration checklist without checking their relevance to the proposed broker.
Weak or Inconsistent Business Plans
A business plan should explain how the applicant intends to operate. General information about the insurance industry does not demonstrate the applicant’s own readiness. Questions can arise when projected income increases significantly without explaining customer acquisition, staffing or servicing capacity.
Another weakness is assuming immediate revenue without providing for initial operating expenses. The plan should connect target customers, proposed services, funding and expenditure. It should also agree with the personnel and infrastructure described elsewhere in the application.
Inadequate Office and Infrastructure Evidence
Office documents may require clarification when addresses differ, the lease has expired or photographs do not clearly relate to the stated premises. Shared premises can also require an explanation of working arrangements and protection of confidential information. The applicant should describe how the available space and facilities support the proposed operations. Before filing, the premises records should be checked for validity, correct parties and consistency with the application.
Unclear Technology and Record-Management Arrangements
Broad statements about secure systems may provide limited information about how the business will actually operate. The applicant should explain how customer information will be collected, accessed, stored and retrieved. Responsibility for user permissions, backups and record management should also be identifiable.
For a digital business, the proposed customer journey should agree with the staffing and technology arrangements. Systems that remain under development should not be described as fully operational.
Delayed or Partial Responses to Queries
A clarification response can prolong scrutiny if it answers only part of the question or submits documents without explaining their relevance. For example, where a query concerns differences between financial figures, providing another certificate without a reconciliation may leave the original issue unresolved.
A clear response should identify each query, answer it directly and reference the relevant attachment. Where a correction affects other documents, those documents should also be reviewed and updated as appropriate.
Changes During the Application Process
Changes in ownership, management, premises, capital or the Principal Officer can affect information already submitted. Such changes may require revised documents and further examination. Confusion increases when updated records are submitted without identifying what has changed. The applicant should assess the implications before implementing a change. Any required update should explain the earlier position, revised position and effective date.
Fee and Payment Reconciliation Issues
Payment-related problems can create administrative obstacles. These may involve an incorrect reference, an amount calculated using outdated instructions or a transaction that cannot be connected to the application.
Applicants should verify the applicable payment requirements and retain the acknowledgement. The payment record should clearly identify the applicant and relevant application. An attempted payment should not be assumed to complete the requirement where the transaction has failed or its status remains uncertain.
Outstanding Approval-Stage Conditions
Submission, scrutiny, conditional communication and final registration are different stages. Progress at one stage does not establish that every requirement has been completed. Outstanding bank documents, insurance evidence or another specified condition may prevent further progress.
The timing should be understood from the applicable requirements and communication received. A condition tracker can identify the pending item, responsible person and evidence needed. Applicants should carefully follow the terms of any conditional communication.
Application Complexity and Additional Examination
Some applications require further examination even where the applicant has prepared carefully. Complex ownership, unfamiliar operating arrangements or information requiring verification can affect the process.
A period without an update does not necessarily establish that a document is missing. The applicant should review the actual status and outstanding correspondence before deciding on the next step. A focused follow-up should identify the application reference, last communication and action taken. Repeated requests for approval without addressing unresolved issues are unlikely to clarify the position.
How to Reduce Avoidable Delays
Preparation should begin before filing. Applicants should confirm their proposed category, review constitutional documents, organise ownership and financial records and establish the status of key appointments. One coordinator should maintain the application file, document index and query tracker.
This reduces the risk that different departments or advisers submit contradictory versions. Management should review the complete submission rather than approve documents individually. After filing, responses should be timely, accurate and supported by records that directly address the questions raised.
Can an IRDAI Approval Date Be Guaranteed?
An approval date should not be treated as assured. The time required depends on the application’s completeness, the matters identified during scrutiny and the applicant’s ability to resolve them. Acknowledgement of an application or payment of a fee does not constitute registration.
The applicant should verify the final approval and applicable conditions before commencing regulated activities. Professional support can improve preparation and coordination, but it cannot replace regulatory scrutiny or guarantee an outcome.
Conclusion
Delays in IRDAI insurance broker licence approval can result from incomplete documents, inconsistent disclosures, unclear funding, unresolved personnel requirements and inadequate responses to queries. Applications involving complex ownership or operating arrangements may also require additional examination.
Applicants can reduce avoidable delays by preparing a consistent file, reconciling financial information and assigning clear responsibility for regulatory correspondence. Each response should resolve the issue raised and explain any changes affecting other application documents.
Frequently Asked Questions (FAQ’s)
Q1. Why is my IRDAI insurance broker licence application delayed?
Ans. Delays may arise from incomplete documents, inconsistent disclosures, unclear financial records or unresolved personnel requirements. The reason for a particular application should be identified from its status and IRDAI’s correspondence.
Q2. Can missing documents delay IRDAI approval?
Ans. Yes. Missing declarations, unsigned forms or incomplete supporting records can lead to clarification requests. Applicants should check the complete file before submission.
Q3. Can differences in financial records affect approval?
Ans. Yes. Differences between capital certificates, bank statements and corporate records may require reconciliation. Financial documents should use clearly identified dates and explain any changes.
Q4. Can Principal Officer documentation cause delays?
Ans. Incomplete qualification, training, examination or appointment records may require further clarification. The Principal Officer’s particulars should match the supporting documents.
Q5. Does foreign investment automatically delay an IRDAI application?
Ans. Foreign investment does not automatically cause delay, but the ownership structure may require additional examination. Clear investor details and supporting records help address questions efficiently.
Q6. How should applicants respond to IRDAI clarification requests?
Ans. Applicants should answer each query directly, attach the relevant evidence and follow the specified deadline. Any correction affecting other application documents should also be addressed.
Q7. Can changes in directors or shareholders affect a pending application?
Ans. Yes. Changes may require updated disclosures, supporting documents and further examination. Applicants should assess the applicable requirements and communicate relevant changes promptly.
Q8. Does payment of the application fee mean the licence is approved?
Ans. No. Fee payment is one part of the application process. The applicant must receive the required registration and satisfy applicable conditions before commencing regulated activities.
Q9. Can a consultant guarantee faster IRDAI approval?
Ans. A consultant can help prepare documents, identify inconsistencies and coordinate responses. Approval and its timing remain subject to IRDAI’s examination and the applicant’s compliance.
Q10. How can applicants reduce avoidable approval delays?
Ans. Prepare a complete application, reconcile ownership and financial records, confirm key appointments and respond promptly to queries. Maintaining a document index and query tracker also helps.
- 29 Oct, 2026
 CA Manish Mishra
- Easing Finance
CA Manish Mishra is the Co-Founder & CEO at GenZCFO. He is the most sought professional for providing virtual CFO services to startups and established businesses across diverse sectors, such as retail, manufacturing, food, and financial services with over 20 years of experience including strategic financial planning, regulatory compliance, fundraising and M&A.