Search GrowthX Learning Content
Eligibility Requirements for SEBI RIA Registration
Investment advisory services require professional knowledge, responsible client handling and compliance with the applicable regulatory context. In India, individuals and entities proposing to provide investment advice for consideration must assess whether registration with the Securities and Exchange Board of India is required.
A SEBI-registered Investment Adviser, commonly known as a Registered Investment Adviser or RIA, provides investment advice within the scope permitted by the registration. Eligibility involves more than passing an examination. Applicants must meet qualification and certification requirements, establish appropriate business arrangements, maintain the prescribed deposit and demonstrate their ability to operate a regulated advisory practice. The eligibility has changed significantly in recent years. Understanding the amended requirements is essential because older descriptions of compulsory experience, finance-specific degrees and minimum net worth may no longer reflect the current position.
In this article, CA Manish Mishra talks about Eligibility Requirements for SEBI RIA Registration.
Legal Structure Governing SEBI RIA Registration
SEBI RIA registration is governed by the SEBI (Investment Advisers) Regulations, 2013, read with applicable amendments, circulars and directions. Regulation 6 addresses eligibility considerations, Regulation 7 prescribes qualification and certification requirements, and Regulation 8 deals with the mandatory deposit. The regulations cover advice relating to securities and securities portfolios, including financial planning within the applicable regulatory scope. Consideration includes economic benefits received or receivable for providing investment advice and is not restricted to a separately identified advisory fee.
For example, a professional who reviews a client’s income, liabilities, existing investments and retirement objectives before recommending securities should assess the Investment Adviser. The classification depends on the actual service rather than whether it is described as financial coaching, wealth guidance or investment mentoring.
Who Can Apply for SEBI RIA Registration?
Individual Applicants and Sole Proprietors
An individual may apply for registration after satisfying the applicable eligibility conditions. A sole proprietor is assessed under the requirements applicable to an individual applicant. This structure may be suitable for a professional establishing an advisory practice under their own ownership.
For example, a qualified professional planning to offer investment consultations and personalised financial plans may consider the individual route. Before applying, the professional should assess the proposed client base, financial resources, certification status and ability to maintain continuing compliance.
Companies, LLPs and Partnership Firms
Non-individual applicants may include companies, limited liability partnerships and partnership firms. These structures can support a business involving multiple professionals, organised management responsibilities and a larger operating model.
However, incorporation alone does not establish eligibility. The entity must satisfy the applicable requirements through its principal officer and relevant personnel, along with its business arrangements, infrastructure, deposit and declarations. A company should therefore identify its advisory team and management responsibilities before preparing the application.
Educational Qualification Requirements
Recognised Graduate Degree or Equivalent Qualification
Following the November 2025 amendments, an eligible qualification route includes a recognised graduate degree or equivalent educational qualification, accompanied by the applicable certification. The current should not be interpreted as requiring every applicant to hold a finance-specific degree.
A graduate from another academic discipline should examine whether their qualification is recognised and then complete the applicable certification requirements. The applicant should retain clear evidence of the qualification, such as the degree certificate and other documents required during assessment.
CFA Charter Route
The amended also recognises a CFA Charter from the CFA Institute as an available qualification route, accompanied by the relevant certification requirements. Applicants should distinguish holding the CFA Charter from merely passing one or more levels of the programme.
A professional relying on this route should ensure that the qualification claimed in the application accurately matches the regulatory requirement. Experience in investment analysis or participation in a professional programme should not be presented as equivalent to completing the prescribed qualification.
Specified NISM Postgraduate Programmes
Specified NISM postgraduate programmes provide an alternative qualification pathway. These include the Post Graduate Programme in Securities Markets focused on Investment Advisory and the Post Graduate Programme in Financial Planning, along with other programmes specified by SEBI.
Applicants relying on this route should confirm that the exact programme falls within the recognised provision. A privately offered course with a similar name should not be assumed to qualify. The programme certificate and supporting records should clearly establish the qualification being relied upon.
Is Previous Work Experience Mandatory?
The earlier minimum experience requirement was removed through the December 2024 amendments. Applicants should therefore avoid relying on older guidance that treats five years of relevant experience as a blanket requirement for every fresh application. However, regulatory eligibility and practical competence are different matters. A person entering the profession without advisory experience should develop an understanding of risk assessment, suitability, portfolio construction and client communication.
Knowledge of stock selection alone may not prepare someone to advise a client with significant liabilities or a short investment horizon. Practical preparation helps an adviser understand how recommendations affect the client’s wider financial position. It also supports the development of procedures for recording information, explaining risks and reviewing advice.
NISM Certification Requirements
Investment Adviser Level 1 and Level 2
The standard advisory certification route includes NISM Series X-A, Investment Adviser Level 1, and NISM Series X-B, Investment Adviser Level 2. Applicants must examine the requirements applicable to their qualification pathway and role.
Certification should be planned before filing the application. Applicants should ensure that the required certificates are valid and that names and identifying details are consistent with other records. Holding a certification for another intermediary category, such as Research Analyst, should not be assumed to satisfy the advisory requirements.
Alternative Qualification and Initial Certification Treatment
Applicants completing specified NISM postgraduate programmes may qualify for the prescribed exemption from initial entry-level certification. This treatment applies to the recognised qualification route and should not be extended to unrelated courses or professional training.
The exemption does not remove continuing certification obligations. Applicants must understand the renewal requirements applicable to their pathway and maintain evidence of compliance.
Certification Renewal
Relevant certification must be renewed within the applicable period to ensure continuity in compliance. For the specified programme route, the provides for relevant renewal certification within three years from the registration certificate.
NISM Series X-C is an Investment Adviser certification renewal examination. Its stated eligibility includes holding valid Series X-A and X-B certificates. It should therefore be understood as a renewal route rather than a substitute entry route for a fresh candidate.
A useful operational practice is to maintain a register showing each relevant person’s qualification, certificate number, validity period and renewal deadline. This helps prevent compliance gaps arising from expired certificates.
Principal Officer Requirements for Non-Individual Applicants
Appointment of an Appropriate Principal Officer
A non-individual applicant must identify an appropriate principal officer with responsibility for the advisory business. The position should reflect genuine operational authority rather than an appointment made only to support the registration application.
The principal officer’s role depends on the entity’s structure and activities. Applicants should establish who will supervise advice, monitor procedures and oversee the work of relevant personnel. Clear responsibility is especially important where the entity has several business divisions.
Qualification and Certification of the Principal Officer
The principal officer must satisfy the applicable qualification and certification requirements. An entity should not assume that the founder’s qualifications are sufficient if another person has been designated to perform the principal officer’s role. Before filing, the entity should verify the designated person’s eligibility and organise the supporting evidence. Appointment documents, role descriptions and application information should present a consistent explanation of the person’s responsibilities.
Partnership Firm Arrangements
In a partnership firm, one partner must be designated as principal officer. Partners engaged in providing investment advice must also meet the applicable qualification and certification requirements. The firm should therefore examine the functions of each partner. A distinction should be maintained between ownership participation and actual delivery of advisory services, while ensuring that the relevant requirements are met by everyone performing regulated advisory functions.
Requirements for Persons Associated with Investment Advice
Personnel Involved in Advisory Functions
Eligibility assessment extends beyond the applicant or principal officer. Relevant personnel associated with investment advice must meet the requirements applicable to their functions.
A person who discusses a client’s circumstances and recommends investments performs a different role from someone who explains subscription terms. Businesses should assess actual duties rather than rely only on job titles such as relationship manager, consultant or customer support executive.
Sales and Other Non-Core Personnel
SEBI’s circular dated 24 June 2026 introduced a lighter certification route for personnel performing only sales and other non-core services. Such personnel may use the prescribed NISM Series XXV-B route, while those involved in investment advice continue under the applicable advisory certification.
This relaxation should be applied according to the work performed. Sales personnel should not move into securities recommendations or personalised investment guidance without meeting the requirements relevant to that activity. Written role descriptions and staff training can help maintain the appropriate boundaries.
Deposit Requirements for SEBI RIA Registration
Deposit Linked to Client Numbers
The current requires a deposit based on the maximum number of clients on any day of the previous financial year. The prescribed deposit is ₹1 lakh for up to 150 clients, ₹2 lakh for 151 to 300 clients, ₹5 lakh for 301 to 1,000 clients and ₹10 lakh for 1,001 clients or more.
Applicants should plan the deposit separately from application fees and operating expenses. The business should also establish a process for monitoring client numbers and reviewing whether the applicable deposit amount needs to change.
Permitted Forms and Lien Arrangements
The deposit may be maintained through permitted deposits with scheduled banks or eligible liquid or overnight mutual fund units, subject to the prescribed arrangements. It must carry the required lien in favour of the relevant administration and supervisory body.
Applicants should follow the current procedural requirements for establishing and documenting the lien. Merely holding the amount in an ordinary business bank account should not be treated as equivalent to meeting the regulatory deposit requirement.
Position on Older Net Worth Requirements
The amended Investment Adviser replaced the earlier net worth requirement with a deposit requirement. Applicants should therefore avoid using the older IA net worth thresholds as the current eligibility test.
Nevertheless, financial planning remains important. Meeting the deposit requirement does not establish that a business has sufficient resources to operate effectively. A realistic budget should account for technology, staffing, professional expenses, documentation and continuing compliance, particularly during the period before revenue becomes stable.
Fit and Proper Requirements
Integrity and Regulatory Background
The applicant and relevant persons must satisfy the applicable fit and proper criteria. Eligibility assessment also considers matters such as regulatory disciplinary action and previous refusal of registration. These requirements demonstrate that academic qualifications alone are insufficient. Applicants should collect accurate background information and make the disclosures required by the application process.
Accurate Declarations and Supporting Explanations
Where a relevant issue exists, it should be disclosed with a factual explanation and supporting documents. An incomplete declaration may create additional concerns during assessment. A previous regulatory matter should be evaluated according to its facts and the applicable criteria. Applicants should neither conceal it nor assume that every historical issue automatically results in rejection.
Part-Time Investment Adviser Eligibility
Nature of Part-Time Registration
The permits part-time Investment Adviser registration subject to conditions governing other activities, segregation and conflicts. Part-time registration is a defined regulatory category rather than simply a description of the hours devoted to advisory work.
An applicant considering this route should examine their existing employment or professional activity and determine whether it is compatible with the prescribed conditions. Other services should be clearly identified and separated from investment advisory services.
Qualifications and Client Limit
Part-time advisers remain subject to applicable qualification and certification requirements. The regulations prescribe a maximum of 75 clients at any point in time. Applicants should therefore consider whether this route matches the expected scale of the practice. A professional planning a substantial advisory business should account for the client restriction before selecting the part-time category.
Eligibility Where the Applicant Conducts Other Activities
A non-individual applicant carrying on other activities may need to organise investment advisory services through a separately identifiable department or division. The application is made by the entity rather than the department itself. Banks and NBFCs must address applicable RBI permission and the prescribed subsidiary or departmental arrangements. Other applicants should examine the separation needed between advisory services and their additional business activities.
A useful preparation exercise is to map every activity and revenue source. Advisory fees, distribution remuneration and unrelated professional income should be described clearly so that potential conflicts and required arrangements can be identified.
Infrastructure and Operational Readiness
Systems for Delivering Advice
The applicant should have infrastructure capable of supporting the proposed advisory business. In practical terms, this means planning how client information will be collected, assessed and used to develop recommendations.
For example, an adviser should be able to explain how a client moves from onboarding to risk assessment, suitability analysis and delivery of advice. The process should be appropriate to the nature and scale of the proposed service.
Record Maintenance and Confidentiality
Reliable systems should support the preservation of agreements, assessments, recommendations and client communications. Appropriate arrangements should also protect confidential information.
A small practice may use relatively simple systems, but those systems should still be dependable. The applicant should know who can access records, how information is stored and how documents will be retrieved when required.
Documents Required to Demonstrate Eligibility
Individual Applicant Records
An individual applicant should prepare the relevant identity and address records, qualification evidence, certification details, business information and applicable declarations. Deposit-related documentation must be organised according to the prescribed procedure. Names and other identifying details should remain consistent across the records. Differences between certificates and identity documents should be addressed before submission wherever possible.
Entity and Personnel Records
A company, LLP or partnership firm should organise its incorporation or constitution documents, ownership and management information, principal officer details and evidence concerning relevant personnel. The documents should support the proposed operating model. For example, the person identified as principal officer should have responsibilities consistent with the appointment records and the application description.
Business Model and Infrastructure Information
Applicants should explain the services they intend to provide, their target clients and the proposed delivery process. Infrastructure details and relevant declarations should accurately describe the arrangements in place.
A precise description is more useful than broad language such as “complete wealth solutions.” The application should explain whether the business will offer consultations, written plans, portfolio advice or ongoing review services.
Application Assessment and Registration
Applications are assessed through the recognised Investment Adviser Administration and Supervisory Body, which recommends qualifying applications to SEBI for registration. The assessment may involve requests for clarification or additional records. Applicants should respond with complete and consistent information rather than provide documents without explaining how they address the query.
Submitting an application or completing certification does not itself authorise the commencement of regulated advisory services. Applicants must complete the applicable registration requirements before operating under the registration.
Transition from Individual to Non-Individual Registration
The current requires an individual adviser exceeding 300 clients or collecting more than ₹3 crore in fees during a financial year, whichever occurs earlier, to initiate the prescribed transition to non-individual registration.
This requirement should form part of growth planning. A practice approaching the thresholds should consider its future legal structure, personnel and documentation early enough to manage the transition properly. Regular monitoring of client numbers and fee collections helps the adviser identify when action is required. Waiting until year-end may be unsuitable where the client threshold is exceeded earlier.
Common Mistakes in Assessing Eligibility
Common errors include relying on outdated experience or net worth requirements, treating any private financial course as a recognised qualification and assuming that NISM certification is equivalent to SEBI registration. Entity applicants may overlook the requirements applicable to advisory personnel or designate a principal officer without clearly assigning responsibilities.
Another frequent issue is a mismatch between the business described in the application and the services promised to customers. A careful review before filing should check qualification routes, certificate validity, personnel roles, deposit arrangements and consistency across documents. This allows routine issues to be resolved before they become application queries.
Continuing Compliance After Registration
Eligibility is the starting point of a regulated advisory practice. After registration, the adviser must continue meeting the applicable qualification, certification, deposit and conduct requirements.
The business should establish responsibility for certificate renewals, client records, compliance reviews, complaints and regulatory deadlines. Changes in personnel, activities or operating arrangements should also be assessed for their regulatory implications. Operational discipline helps ensure that the business remains consistent with the basis on which registration was granted.
Conclusion
Eligibility for SEBI RIA registration combines recognised qualifications, applicable certification, deposit arrangements, suitable personnel and readiness to operate a regulated advisory business. Recent amendments have broadened qualification routes and removed older requirements, but applicants must still satisfy the complete.
A strong application begins with a clearly defined service, the appropriate legal structure and supporting records that accurately demonstrate eligibility. Preparing these elements together provides a sound foundation for registration and for delivering responsible investment advice.
Frequently Asked Questions (FAQ’s)
Q1. Who can apply for SEBI RIA registration?
Ans. Individuals, sole proprietors, companies, LLPs and partnership firms may apply, subject to the applicable eligibility requirements. Applicants must satisfy qualification, certification, deposit, fit and proper, and infrastructure requirements. Non-individual applicants must also identify an eligible principal officer.
Q2. Is a finance degree compulsory for RIA registration?
Ans. No. Under the amended, a recognised graduate degree or equivalent educational qualification is an available eligibility route, accompanied by the applicable certification. Applicants from non-finance backgrounds can therefore qualify if they satisfy the remaining requirements.
Q3. Is five years of work experience mandatory?
Ans. The earlier minimum experience requirement was removed through the December 2024 amendments. Fresh applicants should not rely on older guidance prescribing five years of experience as a blanket requirement. They must still fulfil the current qualification, certification and other eligibility conditions.
Q4. Which NISM examinations are generally required?
Ans. The standard advisory certification route includes NISM Series X-A, Investment Adviser Level 1, and NISM Series X-B, Investment Adviser Level 2. Specified alternative qualification routes may have different initial certification treatment. Applicants must also meet the relevant renewal requirements.
Q5. Does passing NISM examinations automatically grant RIA registration?
Ans. No. NISM certification is only one component of eligibility. Applicants must complete the registration process and satisfy the other applicable conditions. Passing the examinations or submitting an application does not independently authorise regulated investment advisory services.
Q6. Can a sole proprietor register as an Investment Adviser?
Ans. Yes. A sole proprietor may apply under the eligibility conditions applicable to an individual. The proprietor must meet the relevant qualification, certification, deposit and other requirements and establish suitable arrangements for delivering advisory services.
Q7. What is the deposit requirement for an RIA?
Ans. The prescribed deposit is ₹1 lakh for up to 150 clients, ₹2 lakh for 151–300 clients, ₹5 lakh for 301–1,000 clients and ₹10 lakh for 1,001 clients or more. The slabs refer to the maximum client count on any day of the previous financial year. Prescribed deposit and lien arrangements must be followed.
Q8. Are the older minimum net worth requirements still applicable?
Ans. The amended IA replaced the earlier net worth requirement with a deposit requirement. Applicants should therefore assess the current deposit rules instead of relying on older IA net worth thresholds. Separate requirements may apply to other regulated activities conducted by the business.
Q9. Does a company or LLP need a qualified principal officer?
Ans. Yes. A non-individual applicant must designate an appropriate principal officer who satisfies the applicable qualification and certification requirements. The person must have genuine responsibility for the advisory business. Relevant advisory personnel must also meet the requirements applicable to their roles.
Q10. Can someone register as a part-time Investment Adviser?
Ans. Yes, subject to the prescribed conditions concerning other activities, conflicts and segregation. Part-time advisers must satisfy the applicable qualification and certification requirements. Their total client count must not exceed 75 at any point in time.
- 12 Oct, 2026
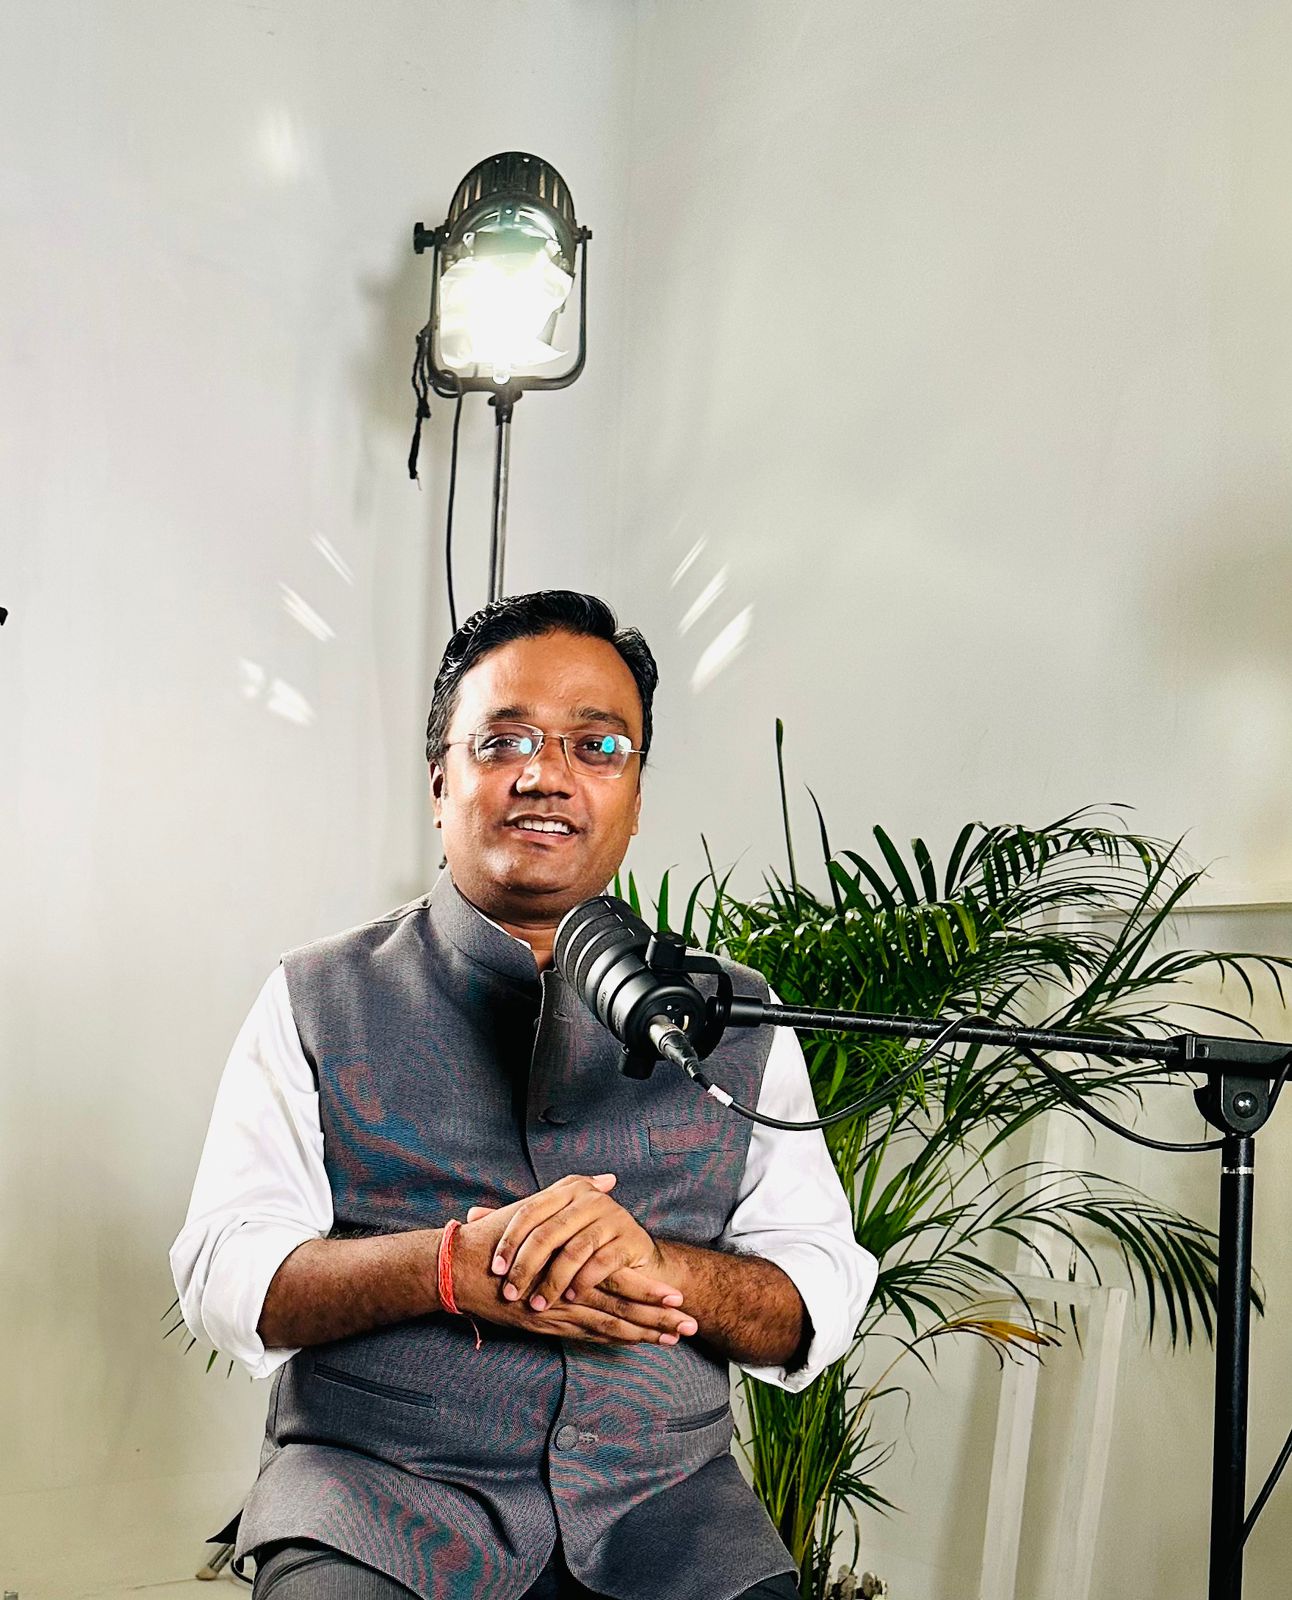 CA Manish Mishra
- Easing Finance
CA Manish Mishra is the Co-Founder & CEO at GenZCFO. He is the most sought professional for providing virtual CFO services to startups and established businesses across diverse sectors, such as retail, manufacturing, food, and financial services with over 20 years of experience including strategic financial planning, regulatory compliance, fundraising and M&A.