Search GrowthX Learning Content
How to Obtain a SEBI Registered Investment Adviser Licence
Starting an investment advisory business in India requires financial knowledge, appropriate qualifications and a clear understanding of regulatory responsibilities. Anyone planning to provide investment advisory services should first assess the applicable registration requirements and prepare the documents, personnel arrangements and operating systems needed for the proposed business.
A SEBI Registered Investment Adviser, commonly called an RIA, operates under the SEBI (Investment Advisers) Regulations, 2013. Although commonly referred to as an investment adviser licence, the formal authorisation is a certificate of registration granted by the Securities and Exchange Board of India. Unless a specific exemption applies, a person must obtain registration before acting or presenting themselves as an investment adviser.
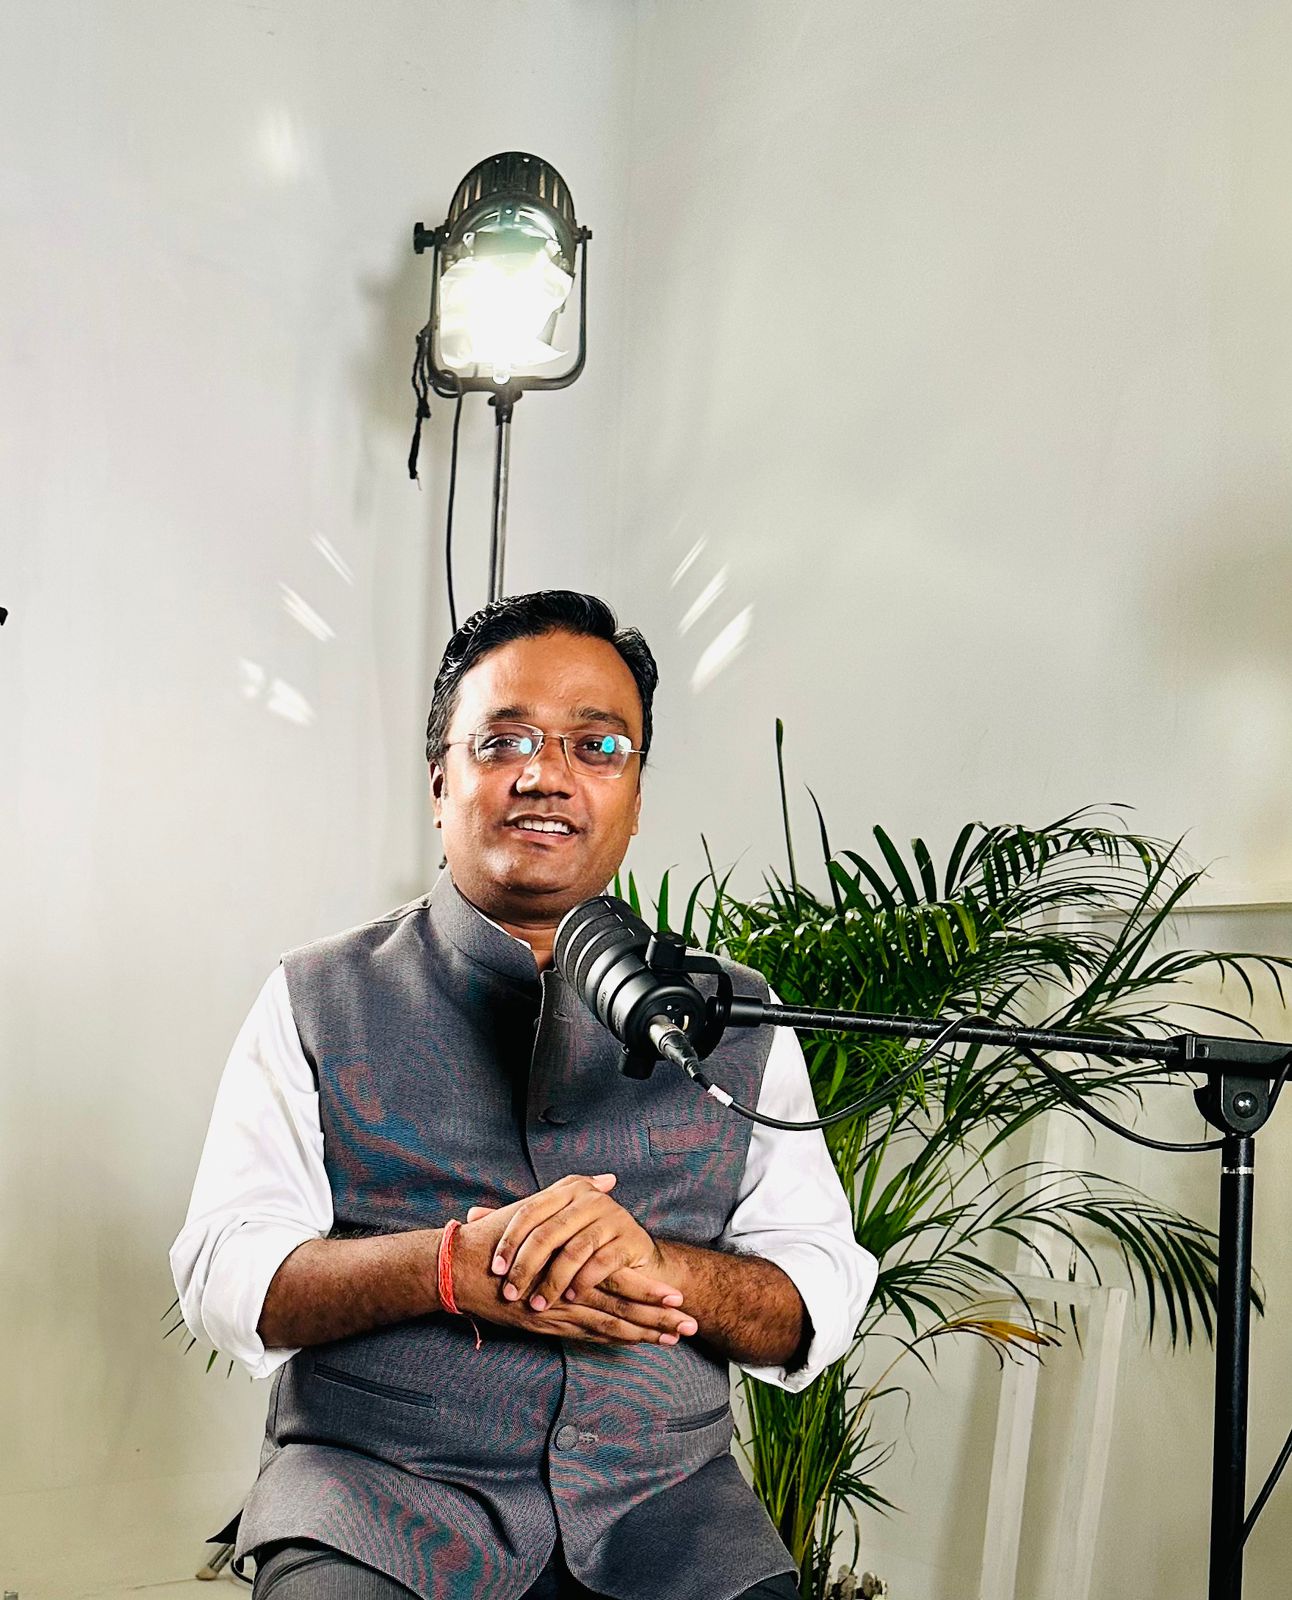
In this article, CA Manish Mishra talks about How to Obtain a SEBI Registered Investment Adviser Licence.
What Is a SEBI Registered Investment Adviser?
A SEBI Registered Investment Adviser provides investment advice within the applicable regulatory framework. Investment advice includes advice concerning investment in, purchase or sale of securities and advice relating to portfolios containing securities. It may be communicated through meetings, written reports, telephone conversations or digital platforms. Financial planning also falls within the regulatory definition.
In practice, an adviser helps clients connect their financial circumstances with their investment objectives. This may involve understanding income, expenses, existing investments, financial commitments and the time available to achieve particular goals. Recommendations should reflect the client’s circumstances and ability to bear investment risk. For example, a client planning to purchase a house within three years may have different investment needs from someone saving for retirement over twenty years. An organised advisory process considers these differences before preparing recommendations.
Who Needs Investment Adviser Registration?
A person proposing to provide investment advice as a business for consideration should assess whether SEBI investment adviser registration is required. Consideration can include economic benefits beyond a direct advisory fee. The assessment should therefore examine how the service operates and how the provider earns income.
The business name alone does not determine the registration requirement. Describing a service as financial coaching, wealth guidance or portfolio support does not settle its regulatory classification. The actual activities, communications and commercial arrangements need to be examined. Certain exemptions apply to specified professionals and intermediaries subject to their conditions. Applicants should assess those conditions carefully rather than assuming that an existing professional qualification or another registration automatically permits a separate investment advisory business.
Who Can Apply for Registration?
Individual Applicants and Sole Proprietors
An individual may apply for investment adviser registration, including where the proposed practice operates as a sole proprietorship. This structure may suit someone establishing an independent advisory business. Before choosing this route, the applicant should assess the expected number of clients, staffing requirements and responsibilities involved in managing the practice. A business plan covering services, costs and anticipated growth can help determine whether an individual structure is suitable.
Partnership Firms
A partnership firm may apply for investment adviser registration. The partners should clearly allocate ownership, management and advisory responsibilities. The partnership deed and internal arrangements should reflect the intended business model. The firm should identify its principal officer and determine which partners or other personnel will provide investment advice, so that their eligibility can be assessed.
Limited Liability Partnerships and Companies
An LLP or company may be suitable where several founders intend to work together, employ an advisory team or develop a larger business. These structures allow the founders to document ownership, decision-making powers and reporting responsibilities. However, forming an entity is only one part of the process. The applicant must also establish appropriate personnel arrangements, prepare the required documents and create systems that support its proposed advisory activities.
Educational Qualifications and Certification Requirements
Recognised Graduate Qualification
The amended eligibility framework provides a route through a recognised graduate degree or equivalent educational qualification together with the relevant NISM or NISM-accredited certification. The framework also recognises a CFA Charter accompanied by the relevant certification.
Applicants should identify the qualification route they intend to rely on and collect the supporting documents. Personal details on degree certificates, identity records and certification documents should be consistent. Differences in names or other particulars should be addressed before filing. Older explanations of the registration process may describe more restrictive educational requirements. Applicants should use the current framework when assessing eligibility.
Experience Requirement
The earlier mandatory experience requirement was removed with effect from December 16, 2024. Applicants must still meet the remaining registration conditions, including the applicable qualification, certification and other eligibility requirements. Practical preparation remains valuable even where a prescribed minimum experience period is no longer required. Understanding financial planning, client communication and the scope of permitted services helps applicants establish an organised advisory practice.
NISM Investment Adviser Certifications
For the standard examination route, the relevant certifications are NISM-Series-X-A: Investment Adviser Level 1 and NISM-Series-X-B: Investment Adviser Level 2. Applicants should plan these examinations early and retain clear copies of the certificates. Passing the examinations establishes certification; it does not itself authorise the person to commence an investment advisory business requiring registration.
Certification validity should also be monitored after registration. Where several people are associated with the practice, maintaining a central certification register helps track expiry dates and future requirements.
Specified NISM Postgraduate Programme Route
The framework recognises specified NISM postgraduate programmes under Regulation 7(c). Eligible applicants using this route are exempt from initial entry-level certification, but must obtain the relevant renewal certification within three years from the date of the registration certificate. Applicants should confirm that their particular programme falls within the recognised route. A general postgraduate degree in finance should not be assumed to provide the same exemption.
Principal Officer and Advisory Personnel
Appointment of the Principal Officer
A non-individual applicant must identify its principal officer in accordance with the applicable requirements. The principal officer’s role should be supported by a clear allocation of management and operational responsibilities. The appointment should reflect how the business will actually operate. Applicants should document who supervises advisory services, manages personnel and coordinates compliance matters.
Persons Associated with Investment Advice
The principal officer and persons associated with investment advice must satisfy the applicable qualification and certification requirements. Relevant partners providing advisory services must also meet these conditions. Applicants should review each person’s actual duties. Preparing an organisation chart and role descriptions helps identify who handles client enquiries, explains services, collects information and communicates recommendations. This supports both application preparation and ongoing supervision.
Fit and Proper Requirements
SEBI considers fit and proper status when assessing an application. Relevant disciplinary history, previous registration refusals and other matters affecting eligibility may require disclosure and examination. Applicants should organise any matter requiring explanation into a separate disclosure file. Where a proceeding or order is relevant, the response should explain the facts and current status and include supporting records. Accurate disclosure is essential. Applicants should check declarations carefully and ensure that the application remains consistent with the documents submitted.
Infrastructure Requirements
Office and Operational Arrangements
The applicant should have infrastructure appropriate to the proposed advisory activities. Its arrangements should support reliable communication, document handling and the effective operation of the business. The infrastructure should reflect the scale and delivery model of the practice. A smaller business may use simpler systems, but still needs clear procedures for managing information and responsibilities.
Technology and Data Management
As practical preparation, applicants should consider secure storage, access controls, backups and reliable methods of retaining client communications and advice records. For an online practice, the client journey should be tested before launch. This includes how information is collected, how documents are signed, how recommendations are communicated and how records are retrieved when required.
Deposit Requirement for Investment Advisers
The prescribed deposit is linked to the maximum number of clients on any day of the previous financial year. The requirement is ₹1 lakh for up to 150 clients, ₹2 lakh for 151 to 300 clients, ₹5 lakh for 301 to 1,000 clients and ₹10 lakh for 1,001 or more clients. Permitted arrangements include a deposit with a scheduled bank or eligible liquid or overnight mutual fund units. The deposit must be marked as a lien in favour of the Investment Adviser Administration and Supervisory Body, commonly called IAASB.
Applicable annual adjustments must be completed by April 30 of the subsequent financial year. Applicants should confirm the required deposit documentation and lien procedure before arranging it. The deposit should be budgeted separately from registration fees and operating expenses. It should not be treated as freely available working capital.
SEBI Investment Adviser Registration Fees
Fees for Individuals and Partnership Firms
For individuals and partnership firms, the SEBI application fee is ₹2,000 and the registration fee for the first five years is ₹3,000. The fee for subsequent five-year periods is ₹1,000. Applicants should confirm applicable taxes and payment instructions before making payments. They should also account for separate IAASB administrative charges.
Fees for Bodies Corporate, Including LLPs
For bodies corporate, including LLPs, the SEBI application fee is ₹10,000 and the registration fee for the first five years is ₹15,000. The fee for subsequent five-year periods is ₹5,000. The overall establishment cost will also depend on certification, entity formation, technology, staffing and compliance arrangements. Registration fees alone do not represent the full cost of starting the business.
Validity of Registration
The certificate remains valid until suspended or cancelled, subject to payment of applicable periodic fees. The five-year fee cycle should therefore be distinguished from an automatic five-year expiry of registration. The practice should maintain reminders for periodic payments and retain evidence of payment in its compliance records.
Documents to Prepare for Registration
Identity and Address Documents
Applicants should organise identity, PAN, address and contact records. Details in these documents should be checked against the application before submission. Where names, addresses or other particulars differ, the applicant should obtain corrections or prepare an appropriate explanation with supporting evidence.
Entity and Constitutional Documents
Entity applicants should assemble incorporation or registration records, constitutional documents and ownership information. They should also organise the authorisations required for signing and submitting the application. The documents should support the proposed business activity and accurately reflect the entity’s ownership and management arrangements.
Qualification and Certification Documents
Educational and certification records should be prepared for each relevant person. Clear labelling makes it easier to review eligibility and respond to personnel-related questions. A personnel register can record each person’s role, qualification route, certification details and validity dates.
Business Plan and Service Description
The business plan should explain the services, intended clients, delivery channels and proposed fee approach. It should describe how the business will operate in practice. For example, a remote advisory practice should explain its arrangements for collecting client information, communicating recommendations and retaining records. Specific descriptions are more useful than broad statements about providing financial solutions.
Operational and Compliance Documents
As preparation, applicants should develop draft client documents, disclosures, complaint procedures and internal responsibilities appropriate to their business. The final attachment list must follow the current category-specific filing checklist. A general document guide should not be treated as an exhaustive list of mandatory attachments.
Step-by-Step Process to Obtain Registration
Step 1: Define the Proposed Services
Begin by explaining what the business will offer, who it will serve and how clients will pay. The description should distinguish the intended advisory services from any other proposed activities. This exercise guides decisions about the applicant structure, personnel, costs and operating systems.
Step 2: Review Eligibility
Check the qualification and certification route for every relevant person. Resolve any eligibility gap before preparing the final filing. For entity applicants, identify the principal officer and advisory personnel early so that their supporting documents can be prepared together.
Step 3: Select the Applicant Structure
Choose the structure after considering ownership, staffing and growth. Where an entity is used, align its constitutional documents and internal responsibilities with the proposed business. Making these decisions before filing reduces the likelihood of needing significant changes during application assessment.
Step 4: Prepare Form A and Supporting Documents
The prescribed application is Form A. Prepare the application and attachments together and check each answer against the supporting evidence. Where an explanation is required, provide a specific response. Avoid relying on generic descriptions that do not accurately represent the applicant’s circumstances.
Step 5: Submit Through the IAASB Channel
BSE Limited acts as the recognised IAASB. It assesses applications and supporting documents and recommends eligible applications to SEBI for registration. Applicants should follow the current official filing instructions and retain a complete copy of the submission, acknowledgements and payment records.
Step 6: Respond to Clarifications
SEBI or IAASB may seek additional information or clarification. Applicants should maintain a tracker showing each query, the required response and the supporting attachment. Responses should answer the question directly. If a clarification changes information supplied earlier, review the rest of the application for consistency.
Step 7: Complete Approval Formalities
Complete the payments, deposit arrangements and other conditions communicated during the approval process. Check the registration certificate carefully when issued. Before commencing services, review whether the client documents, personnel responsibilities, payment systems and record-storage arrangements are ready for use.
Reasons for Registration Delays
Avoidable preparation problems include inconsistent information, missing or unreadable attachments, unclear qualification evidence and an incomplete explanation of the business model. Delays may also arise where responses do not address the specific clarification requested. A careful review before submission and a structured approach to queries can reduce unnecessary exchanges. A complete application improves reviewability, but does not guarantee approval or a particular processing time. Launch plans should allow for assessment and clarification rounds.
Compliance After Registration
Client Onboarding and Risk Profiling
Investment advisers must undertake risk profiling and suitability assessment as required by the regulatory framework. The onboarding process should support the collection and assessment of relevant client information. The practice should establish a consistent workflow so that recommendations are prepared only after the necessary information has been obtained and reviewed.
Suitability of Recommendations
Recommendations should reflect the client’s circumstances, objectives and risk profile. The practice should document the reasoning supporting its advice. Maintaining a clear explanation helps the adviser communicate with the client and supports the review of advice records.
Record Maintenance
Investment advisers must maintain prescribed records. The practice should organise client documents, advice records and relevant communications so they can be retrieved when needed. Access controls and backups help protect these records and support continuity of operations.
Conflicts of Interest
Investment advisers must manage conflicts and act in a fiduciary capacity towards clients. The practice should assess how its ownership, remuneration and other activities may affect the advice provided. Internal procedures should explain how potential conflicts are identified, reviewed and addressed.
Annual Compliance Audit
An annual compliance audit forms part of the continuing obligations. Maintaining organised records throughout the year makes the audit process easier to manage. The business should assign responsibility for coordinating the audit, addressing findings and retaining evidence of corrective action.
Compliance Calendar
A practical compliance calendar should cover periodic fees, certification validity, deposit review, reporting and audit work. Each item should have an assigned owner and a completion record. The calendar should be updated as personnel, client numbers and business activities change.
Conclusion
Obtaining a SEBI Registered Investment Adviser licence is an important step towards establishing a regulated investment advisory business in India. Applicants should begin by defining their services, selecting a suitable business structure and confirming the eligibility of relevant personnel. Educational qualifications, certifications, supporting documents and financial arrangements should be reviewed before submission. A complete application with consistent information helps reduce avoidable clarification requests. Responding accurately and promptly to queries also supports the assessment process, although registration remains subject to regulatory approval.
After registration, advisers must maintain systems that support compliance and responsible client service. Clear allocation of duties, proper client onboarding, risk profiling, suitability assessment and organised advice records should form part of everyday operations. A practical compliance calendar helps track certification validity, reporting, periodic fees, deposit reviews and audit requirements. Regular internal reviews help identify gaps early, protect client interests and support the sustainable growth of the investment advisory practice.
Frequently Asked Questions (FAQ’s)
Q1. What is a SEBI Registered Investment Adviser licence?
Ans. A SEBI Registered Investment Adviser licence is formally a certificate of registration issued under the SEBI (Investment Advisers) Regulations, 2013. It authorises the registered individual or entity to provide investment advisory services within the applicable regulatory framework.
Q2. Who needs SEBI investment adviser registration?
Ans. A person engaged in the business of providing investment advice for consideration generally needs registration unless a specific exemption applies. The requirement depends on the actual services and commercial arrangements, rather than the business name alone.
Q3. Can an individual apply for investment adviser registration?
Ans. Yes, an individual, including a sole proprietor, can apply. The applicant must meet the applicable qualification, certification, deposit and other eligibility requirements.
Q4. Can a company or LLP obtain registration?
Ans. Yes, companies, LLPs and partnership firms can apply. Relevant personnel, including the principal officer and persons associated with investment advice, must satisfy the applicable qualification and certification requirements.
Q5. Is a postgraduate degree compulsory?
Ans. No, a postgraduate degree is not universally compulsory. The amended framework provides an eligibility route through a recognised graduate degree or equivalent qualification together with the relevant certification. Other recognised qualification routes are also available.
Q6. Which NISM certifications are required?
Ans. For the standard examination route, the relevant certifications are NISM-Series-X-A: Investment Adviser Level 1 and NISM-Series-X-B: Investment Adviser Level 2. Applicants relying on a specified alternative qualification route should check its particular certification conditions.
Q7. Can I start providing investment advice after passing NISM examinations?
Ans. Passing the examinations does not itself grant SEBI registration. A person must complete the registration process before undertaking activities that require investment adviser registration.
Q8. Is prior work experience mandatory?
Ans. The earlier mandatory experience requirement was removed with effect from December 16, 2024. Applicants must still satisfy the remaining eligibility conditions. Practical knowledge remains valuable for operating an advisory business effectively.
Q9. What is the minimum deposit requirement?
Ans. The prescribed deposit starts at ₹1 lakh for up to 150 clients. It increases to ₹2 lakh for 151–300 clients, ₹5 lakh for 301–1,000 clients and ₹10 lakh for 1,001 or more clients, based on the applicable client-count framework.
Q10. What are the SEBI registration fees?
Ans. For individuals and partnership firms, the application fee is ₹2,000 and the initial registration fee is ₹3,000. For bodies corporate, including LLPs, these amounts are ₹10,000 and ₹15,000 respectively. Applicable taxes, IAASB administrative charges and other establishment expenses are separate.
- 06 Oct, 2026
 CA Manish Mishra
- Starting Up
CA Manish Mishra is the Co-Founder & CEO at GenZCFO. He is the most sought professional for providing virtual CFO services to startups and established businesses across diverse sectors, such as retail, manufacturing, food, and financial services with over 20 years of experience including strategic financial planning, regulatory compliance, fundraising and M&A.