Search GrowthX Learning Content
AIF vs PMS: Which Investment Structure Is Suitable?
Alternative Investment Funds (AIFs) and Portfolio Management Services (PMS) are two investment arrangements that provide access to professional investment management. Although both are commonly considered by investors with substantial investible capital, they differ in their structure, ownership arrangements, investment strategies, liquidity and costs.
Choosing between AIF and PMS requires more than comparing past returns. Investors must consider how much capital they can allocate, when they may need that money, how much risk they can absorb and whether the proposed strategy complements their existing investments. Understanding these differences helps investors select an arrangement that fits their financial objectives.
In this article, CA Manish Mishra talks about AIF vs PMS: Which Investment Structure Is Suitable?
What Is an Alternative Investment Fund?
An Alternative Investment Fund is a privately pooled investment vehicle that collects capital from investors and invests it according to a defined investment policy. In India, AIFs operate within SEBI’s regulatory framework and may be established as trusts, companies, limited liability partnerships or other permitted bodies corporate.
Investors generally subscribe to units or interests in an AIF scheme. The investment manager combines their contributions and deploys the capital within the fund’s mandate. The investor therefore participates in the performance of a common investment portfolio rather than receiving a separately managed account containing the underlying assets. For example, a private equity AIF may invest pooled capital in several growing businesses. The manager selects those businesses, monitors their development and seeks suitable exits. Investors receive distributions according to the fund documents and the results achieved.
Category I AIF
Category I AIFs focus on specified investment areas such as venture capital, small and medium enterprises, infrastructure, social impact and special situations. Their investment objectives may involve financing emerging businesses, supporting infrastructure development or addressing opportunities within a specialised segment.
The risks vary considerably across these strategies. A venture capital investment may fail because a business cannot establish a sustainable market. An infrastructure investment may experience construction delays or changes in expected cash flows. Investors should therefore evaluate the specific strategy rather than assume that the category itself indicates a particular level of safety.
Category II AIF
Category II AIFs include funds that do not fall within Category I or Category III. Private equity funds and debt funds are common examples. These funds operate under restrictions on borrowing and leverage, subject to applicable permissions and conditions.
A private equity fund may acquire stakes in established businesses and seek to increase their value through expansion, operational improvements or restructuring. A debt fund may seek returns through interest and repayment of principal. Private equity investors face business and exit risks, while debt investors face borrower default, security enforcement and recovery risks.
Category III AIF
Category III AIFs employ diverse or complex trading strategies and may use derivatives and leverage within applicable limits. Their approaches may include long-short investing, arbitrage and other actively managed market strategies. Some funds also follow long-only approaches.
Investors should examine how the strategy generates returns, the extent of market exposure and the controls used to manage losses. A strategy described as hedged or market-neutral can still experience losses arising from execution problems, unexpected market relationships, liquidity constraints or leverage.
What Are Portfolio Management Services?
Portfolio Management Services involve a professional portfolio manager managing or advising on an individual client’s portfolio under an agreed mandate. In a typical arrangement, securities and other permitted assets are held for the client through the relevant account and custody arrangements. PMS allows an investor to access professional research, investment selection and portfolio monitoring. However, an individual account does not automatically mean that the investment strategy is entirely customised.
A provider may apply a common strategy across several clients, with differences arising from contribution dates, withdrawals, restrictions and purchase prices. For example, two investors using the same equity PMS strategy may own similar companies but achieve different returns because they entered at different times. The service agreement should explain the manager’s authority, investment approach, fees and reporting arrangements.
Discretionary PMS
In discretionary PMS, the portfolio manager makes investment decisions within the agreed mandate. The manager selects securities, determines allocations and decides when to buy or sell without seeking approval for every transaction. This arrangement may suit investors who want to delegate routine investment management. The investor retains ownership of the portfolio and receives reports, while the manager exercises investment discretion. Suitability therefore depends heavily on whether the investor understands and accepts the manager’s approach.
Non-Discretionary PMS
In non-discretionary PMS, investment decisions involve the client’s directions or approval according to the agreement. The manager may provide research and recommendations, but implementation reflects the client’s participation. This approach may suit investors who want greater involvement in their portfolio. It also requires time and sufficient knowledge to assess recommendations. Delayed approvals or inconsistent decisions can affect implementation and investment outcomes.
Advisory Services
Under an advisory arrangement, the portfolio manager provides investment recommendations while the client remains responsible for implementation under the service terms. The precise responsibilities for execution and monitoring should be clearly understood. This arrangement may suit investors who want professional guidance while retaining decision-making authority. Its effectiveness depends partly on the investor’s ability to implement recommendations consistently and review the portfolio when circumstances change.
Investment Structure and Ownership
Ownership in an AIF
An AIF investor generally owns units or an interest in the fund rather than directly owning a separately managed selection of its underlying investments. Investment decisions are made at the fund level according to the stated policy. Investors may have voting or consent rights on specified matters, such as certain changes to fund terms. However, they ordinarily do not approve routine investment transactions. The arrangement requires acceptance of a common mandate and the manager’s decision-making process.
Ownership in PMS
In PMS, investments are maintained for the individual client. Reporting generally provides visibility into holdings, transactions, cash balances and expenses. This can help investors understand how their money is deployed and assess its relationship with other investments. Ownership should be distinguished from control. In discretionary PMS, the client owns the assets, but the manager makes investment decisions within the agreement. Investors who want transaction-level involvement should confirm whether the selected service supports it.
Minimum Investment and Financial Suitability
Under the established conventional frameworks, the general minimum investment has been ₹1 crore for an AIF and ₹50 lakh for conventional PMS, subject to applicable exceptions and special arrangements. Accredited investors and certain other eligible participants may receive different treatment. Separate routes must also be distinguished from conventional PMS. The September 2026 approval of the Portfolio Managers Route for Investing in Mutual Fund Units, commonly called PRIM, envisages a ₹25 lakh entry threshold.
Investors should confirm the applicable notified implementation conditions and availability before relying on this route. Meeting an entry threshold does not mean that allocating that amount is financially appropriate. An investor must retain sufficient resources for emergencies, liabilities and other goals. Committing most of one’s investible wealth to a single fund or strategy can create excessive concentration even when the investment meets regulatory eligibility requirements.
Investment Strategy and Opportunities
Investment Opportunities Through AIFs
AIFs may provide access to private equity, venture capital, private credit, infrastructure and specialised listed-market strategies. Some of these opportunities can be difficult for individual investors to access or evaluate independently. The potential benefit comes from the underlying opportunity and the manager’s capabilities. Private-market access alone does not establish that an investment will generate attractive returns. Investors should assess investment pricing, business quality, expected cash flows and the practical route to an exit.
Investment Opportunities Through PMS
PMS can provide professional management of listed securities and other permitted investments according to the selected mandate. A provider may specialise in a particular investment style, market segment or asset allocation approach. Investors should understand why the strategy is expected to add value and whether it duplicates their existing portfolio. A service that owns substantially the same assets as an investor’s other investments may increase costs without providing meaningful diversification.
Customisation and Investor Involvement
Customisation in AIFs
An AIF follows a common investment policy for its scheme. Individual investors generally cannot ask the manager to remove a particular company from their portion of the pooled portfolio. Certain contractual rights or arrangements may be available, but they should be assessed through the fund documents. Investors must be comfortable with the overall mandate because their ability to influence individual investment decisions is usually limited.
Customisation in PMS
Some PMS providers may accommodate restrictions, such as excluding a sector or limiting exposure to an existing holding. The extent of flexibility depends on the provider, strategy and client agreement. Investors should confirm these arrangements before onboarding. Restrictions can affect portfolio construction and cause an individual account’s performance to differ from the provider’s standard strategy.
Liquidity and Investment Horizon
Liquidity in AIFs
Category I and Category II AIFs are generally close-ended and have a regulatory minimum tenure of three years, although actual fund terms may be considerably longer. Category III funds may be open-ended or close-ended.
Private-market funds often need time to develop investments and secure exits. Distributions may depend on a business sale, refinancing or another transaction. Investors should read the provisions covering tenure extensions, transfer restrictions and remaining unsold assets. An expected maturity date should not be treated as a guaranteed date for receiving all capital.
Liquidity in PMS
A PMS portfolio holding liquid listed securities may offer greater practical withdrawal flexibility. Nevertheless, withdrawal can require asset sales and settlement, and contractual conditions or applicable charges may affect the process. The underlying holdings also matter. A portfolio containing thinly traded securities may be difficult to liquidate during stressed markets. Investors should assess both the withdrawal terms and the potential cost of selling assets at an unfavourable time.
Capital Commitments and Funding Requirements
Capital Calls in AIFs
Some AIFs collect a commitment and request contributions in stages through capital calls. For example, an investor may commit ₹1 crore but initially contribute only ₹20 lakh, with the balance payable as the fund identifies investments.
The unpaid commitment remains an obligation under the documents. Investors must retain enough accessible money to meet future calls. Failure to contribute can result in contractual consequences. Financial planning must therefore account for both invested capital and the amount that remains callable.
Contributions in PMS
PMS commonly involves an initial contribution of money or eligible securities, followed by further additions when agreed. The manager deploys the assets according to the mandate and market opportunities. Investors should understand the contribution process, withdrawal arrangements and treatment of assets transferred into the account. Existing securities may require review to determine whether they fit the strategy and what tax consequences could arise from subsequent sales.
Risks Associated with AIFs
Illiquidity Risk
Illiquidity risk arises when an investment cannot be converted into cash within the investor’s required timeframe. Private businesses and specialised debt investments may lack an active market, making exits dependent on negotiations or specific transactions. A delayed exit can create difficulties even when the investment retains value. Investors should allocate capital that they can leave invested for the expected duration and potential extensions.
Business and Credit Risk
Business risk arises when a portfolio company fails to achieve its operating or financial objectives. Competition, weak management, changing demand or financing difficulties can reduce its value. Credit risk arises when a borrower fails to pay interest or repay principal. Security or collateral may improve recovery prospects, but it does not guarantee full or timely recovery. These risks must be evaluated through the fund’s selection and monitoring processes.
Valuation Risk
Unlisted investments require valuation methods involving assumptions and judgement. Reported values may differ from the prices eventually achieved in a sale. Investors should understand how valuations are prepared and reviewed. Limited changes in reported valuations do not necessarily mean that an investment has low economic risk.
Concentration and Control Risk
A fund concentrated in a few companies, sectors or transactions may suffer substantial losses if those exposures perform poorly. Diversification within the fund should therefore be assessed alongside its stated investment focus. Where leverage is used, losses can be amplified and liquidity pressures can increase. Investors should understand the extent of borrowing or derivative exposure and the circumstances in which additional obligations may arise.
Risks Associated with PMS
Market and Investment Selection Risk
PMS portfolios can decline when market conditions weaken. Individual investments can also suffer losses because of company-specific developments, regardless of broader market performance. Professional management does not eliminate these risks. Investors should examine the strategy’s investment discipline, valuation approach and experience during difficult market periods.
Concentration and Liquidity Risk
A focused PMS portfolio may experience substantial volatility because a small number of holdings contribute heavily to performance. Concentration may be intentional, but it must match the investor’s risk capacity. Liquidity risk becomes important when holdings cannot be sold easily. Investors should assess whether portfolio size and trading volumes allow the manager to exit positions without significantly affecting prices.
Turnover and Behavioural Risk
Frequent trading can increase transaction costs and accelerate the realisation of taxable gains. Investors should understand the strategy’s expected turnover and its implications. Behavioural risk arises when investors react inconsistently to market movements. Entering after strong performance and withdrawing during a downturn can damage long-term outcomes. A suitable strategy should be one the investor can reasonably maintain through difficult conditions.
Fees and Expenses
Fees in AIFs
AIF expenses may include management fees, operating costs and performance-related compensation. Some funds use carried interest and a distribution waterfall to determine how capital and profits are shared. The fee calculation base matters. Charges on committed capital may differ significantly from charges on invested capital or net asset value. Investors should also examine expense limits and the treatment of fees during extensions.
Fees in PMS
PMS costs may include management fees, performance fees, brokerage, custody charges and applicable taxes on services. Comparing only the quoted management fee can understate the total cost. Where performance fees apply, investors should understand the hurdle rate and high-water mark. These provisions determine when fees become payable and whether recovering earlier losses can trigger further charges under the agreement.
Tax Considerations
Taxation of PMS Investments
Tax consequences generally arise at the client level because PMS investments are held for the individual investor. Sales, interest and dividends may be treated differently under applicable tax rules. A manager’s sale can create a tax consequence even when the proceeds remain in the account and are reinvested. Investors should therefore consider turnover, realised gains and the information supplied for tax reporting.
Taxation of AIF Investments
Category I and Category II AIFs have historically operated under a statutory pass-through framework for qualifying non-business income, while business income and losses involve separate conditions. Category III funds do not receive the same automatic treatment merely because they are AIFs. The specific scheme’s tax treatment should be assessed under the law applicable to the relevant period. Investors should also understand whether taxable income can arise before an equivalent cash distribution is received.
Performance Evaluation
Assessing PMS Performance
PMS performance should be reviewed after relevant fees and compared with an appropriate benchmark. Investors should examine consistency, drawdowns and results across different market conditions. An individual account may perform differently from published strategy figures because of contribution timing, withdrawals and restrictions. The provider should explain how its reported returns are calculated.
Assessing AIF Performance
Private-market AIF performance requires examination of both reported valuations and actual cash flows. Internal Rate of Return considers cash-flow timing, while measures such as Distributions to Paid-In Capital show how much cash has been returned. Investors should distinguish realised gains from estimated remaining value. A strong valuation-based return may not yet have produced cash that investors can use.
Which Structure May Be Suitable?
When PMS May Be Suitable
PMS may suit investors seeking professional management of an individual portfolio, visibility into transactions and an investment approach compatible with their existing holdings. Its suitability depends on the strategy, costs and withdrawal requirements. Investors should assess whether the service offers sufficient value and whether they can tolerate the portfolio’s likely volatility.
When an AIF May Be Suitable
An AIF may suit investors seeking a defined specialist strategy who have sufficient surplus capital to accept its liquidity and commitment terms. Private-market allocations require patience and an understanding of business, credit, valuation and exit risks. The investment should have a clear purpose within the wider portfolio and remain proportionate to the investor’s financial capacity.
Using AIF and PMS Together
Investors may use both structures for different objectives. PMS could provide managed listed-market exposure, while an AIF could provide a specialist private-market allocation. However, combining structures does not automatically diversify risk. Investors should assess overlap in companies, industries and economic exposures before deciding whether the combination improves the portfolio.
Conclusion
Choosing between Alternative Investment Funds and Portfolio Management Services requires an assessment of an investor’s financial goals, available capital, investment horizon and tolerance for losses. PMS may suit investors seeking professional management of an individual portfolio, visibility into holdings and flexibility within the agreed mandate. An AIF may suit those seeking pooled investment strategies, including private equity, private credit or other specialised opportunities. However, investors must be comfortable with the strategy’s complexity, funding obligations and potential restrictions on accessing their money.
Before committing capital, investors should examine the underlying assets, investment manager’s experience, fee structure, tax implications and withdrawal or exit conditions. Past performance alone should not determine the choice, as future outcomes depend on market conditions and investment execution. The selected arrangement should complement existing investments, preserve sufficient liquidity for financial commitments and maintain an acceptable level of concentration. Suitability ultimately depends on how the strategy supports the investor’s circumstances.
Frequently Asked Questions (FAQs)
Q1. What is the main difference between AIF and PMS?
Ans. An AIF pools money from multiple investors and invests it according to a common investment policy. Investors generally hold units or interests in the fund. PMS involves managing or advising on an individual client’s portfolio, with assets held for that client under the applicable account arrangements.
Q2. Which is more suitable for an investor: AIF or PMS?
Ans. PMS may suit investors seeking professional management of an individual portfolio and visibility into their holdings. An AIF may suit investors seeking a pooled specialist strategy, including private-market opportunities. Suitability depends on the investment strategy, liquidity requirements, costs, investment horizon and capacity to absorb losses.
Q3. Are AIF investments always riskier than PMS?
Ans. Neither structure is automatically riskier than the other. A concentrated equity PMS may experience significant volatility, while an AIF may face business, credit, valuation or liquidity risks. Investors should assess the underlying assets, concentration and use of leverage rather than judge risk solely by the structure.
Q4. Do AIF and PMS guarantee returns?
Ans. No. Neither AIF nor PMS guarantees returns simply because it is professionally managed or regulated. Investment values can decline, and investors may lose capital. Expected returns, target returns and historical performance should not be treated as promises of future results.
Q5. Can investors withdraw money whenever they want?
Ans. Withdrawal flexibility depends on the arrangement. A close-ended AIF generally restricts exits according to its tenure and fund documents. An open-ended AIF may have redemption windows and notice requirements. PMS withdrawals depend on the agreement, applicable conditions and the liquidity of the underlying holdings.
Q6. Can an investor customise investments in AIF or PMS?
Ans. An AIF generally follows a common mandate, so individual investors ordinarily cannot select or exclude its underlying investments. Some PMS providers may accommodate client restrictions, such as avoiding a sector or limiting exposure to an existing holding. The available flexibility should be confirmed in the agreement.
Q7. What is a capital call in an AIF?
Ans. A capital call is a request for an investor to contribute part of the amount previously committed to a fund. Some AIFs collect capital in stages as investment opportunities arise. Investors must maintain sufficient liquidity to meet these obligations and understand the contractual consequences of failing to contribute.
Q8. How should investors compare AIF and PMS fees?
Ans. Investors should compare the total cost, including management fees, performance-related charges, operating expenses and transaction costs, where applicable. They should also examine the fee calculation base, hurdle rate and high-water mark provisions. Comparing returns after expenses provides a more useful assessment than comparing headline fees alone.
Q9. Can an investor invest in both AIF and PMS?
Ans. Yes. An investor may use PMS for managed listed-market exposure and an AIF for a specialist allocation. However, holding both does not automatically create diversification. Investors should examine overlap in companies, sectors and economic risks, as well as the combined liquidity requirements.
Q10. What documents should investors review before investing?
Ans. For an AIF, investors should review the Private Placement Memorandum, contribution agreement and relevant fund documents. For PMS, they should examine the disclosure document and client agreement. Particular attention should be given to the investment mandate, risks, fees, reporting, withdrawal terms, valuation methods and conflict-of-interest provisions.
- 03 Oct, 2026
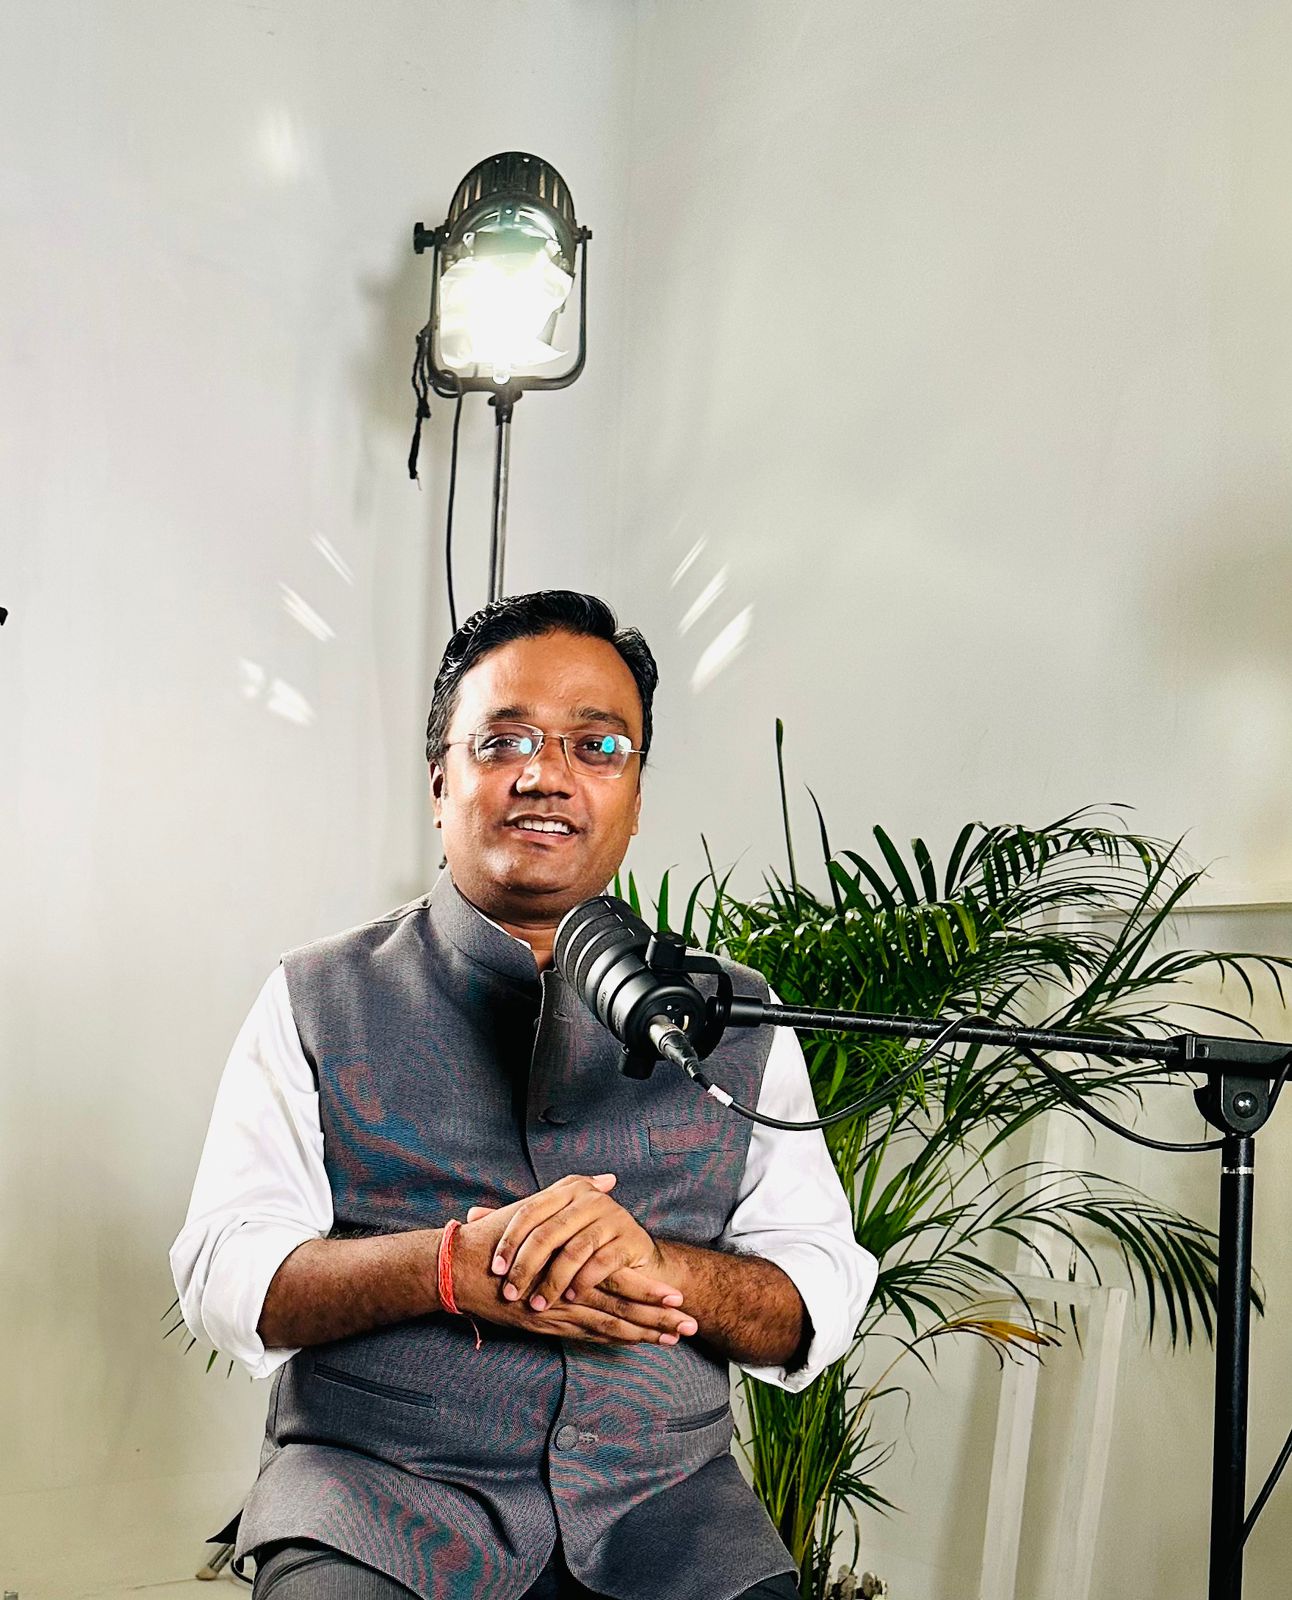 CA Manish Mishra
- Easing Finance
CA Manish Mishra is the Co-Founder & CEO at GenZCFO. He is the most sought professional for providing virtual CFO services to startups and established businesses across diverse sectors, such as retail, manufacturing, food, and financial services with over 20 years of experience including strategic financial planning, regulatory compliance, fundraising and M&A.