Search GrowthX Learning Content
Net-Worth Requirements for Investment Advisers in India
Establishing an investment advisory business in India requires an understanding of both professional eligibility and financial compliance. Individuals and entities planning to obtain registration with the Securities and Exchange Board of India often ask how much capital they need, whether they must submit a net worth certificate and whether the older financial thresholds remain applicable. These questions arise because many older articles and registration checklists refer to minimum net tangible assets of ₹5 lakh for individual Investment Advisers and minimum net worth of ₹50 lakh for non-individual Investment Advisers.
The current position is that the SEBI Investment Adviser has replaced these earlier minimum net worth requirements with a mandatory deposit requirement. Applicants must therefore distinguish historical rules from the financial conditions applicable today. This change does not mean that an advisory business can operate without adequate funds. The regulatory deposit, registration expenses, capital contributions and day-to-day operating funds serve different purposes. Understanding these differences helps applicants prepare accurate documents and develop a realistic business budget.
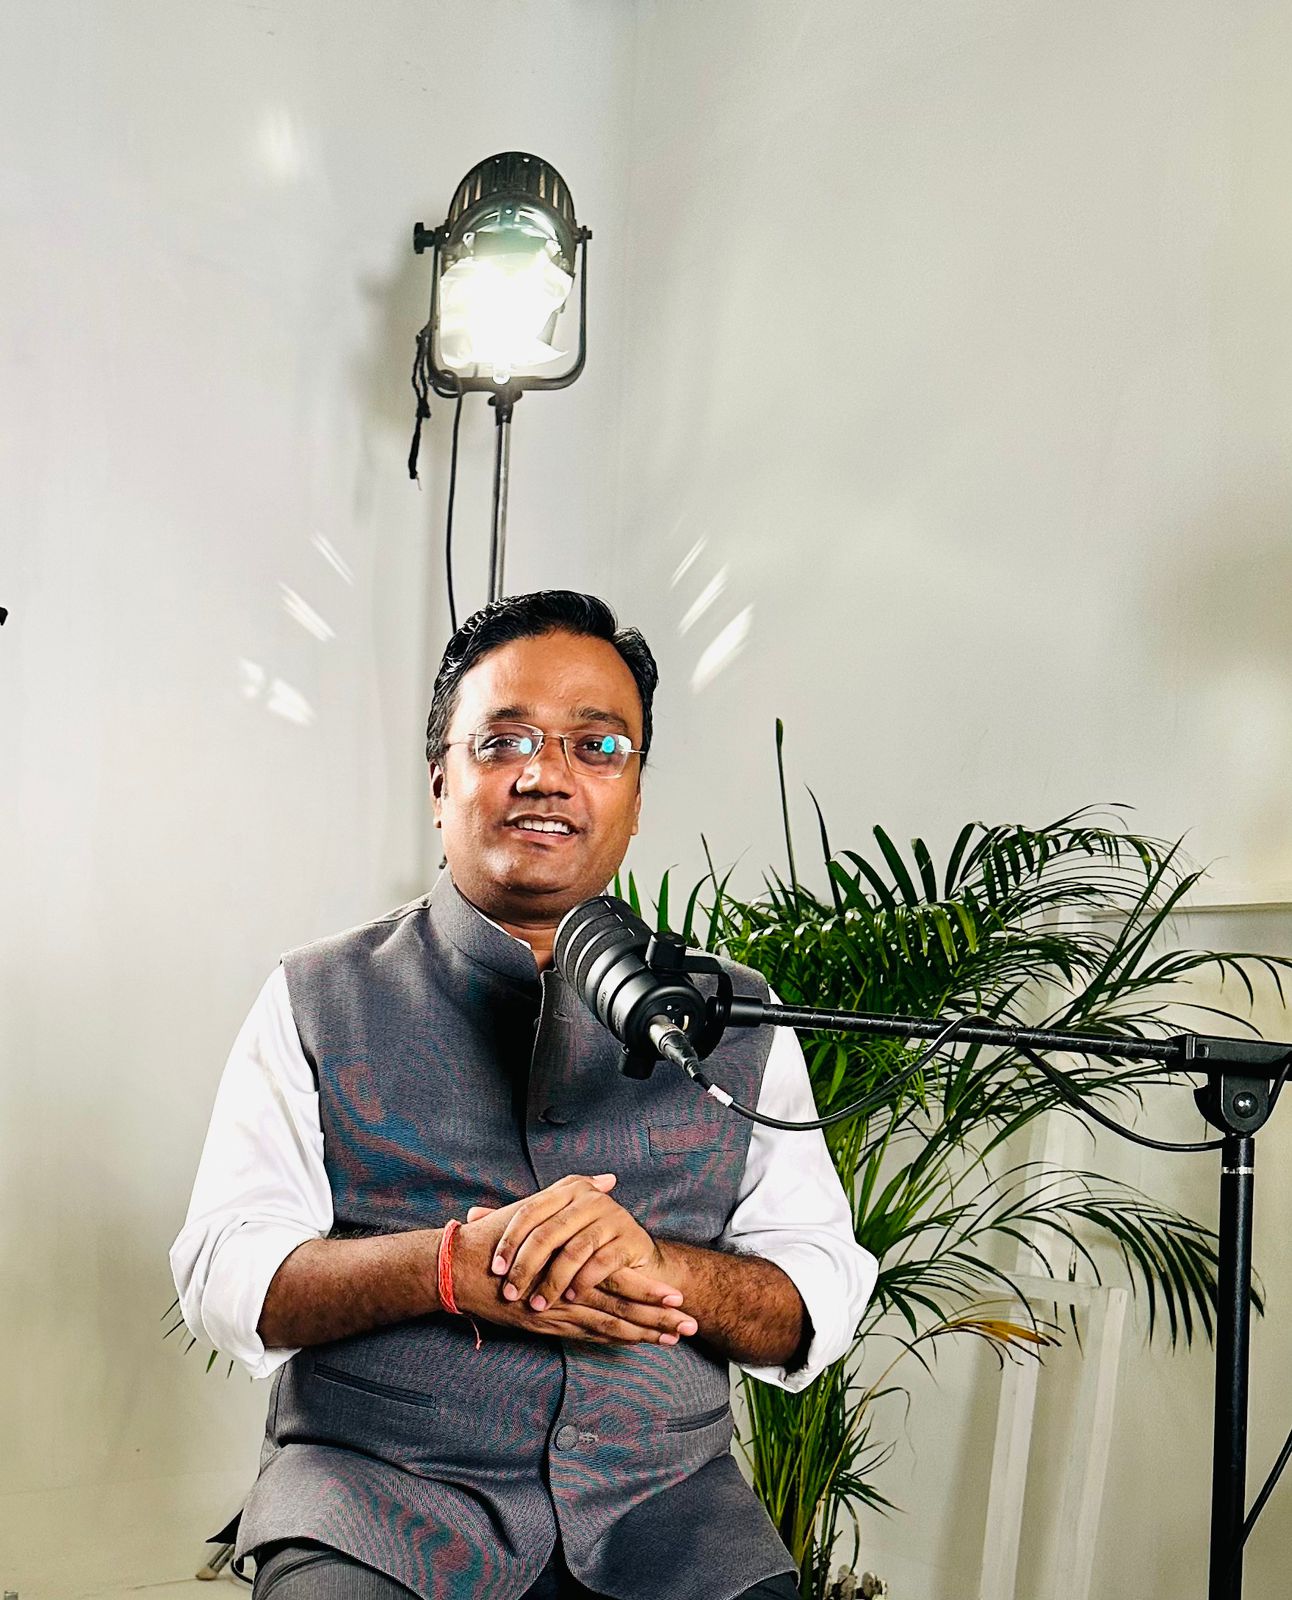
In this article, CA Manish Mishra talks about Net-Worth Requirements for Investment Advisers in India.
Legal Structure Governing Financial Requirements
SEBI Investment Adviser Regulations
Investment Advisers are governed by the SEBI (Investment Advisers) Regulations, 2013, together with subsequent amendments, circulars and directions. The regulates eligibility, qualifications, certification, financial requirements, professional conduct and continuing compliance.
Regulation 8 is particularly relevant to the financial requirement. Under its earlier version, the provision required advisers to maintain prescribed levels of net worth or net tangible assets. The applicable threshold depended on whether the adviser was an individual or a non-individual entity. When preparing an application, it is essential to read the amended provision. A checklist created under an earlier version of the regulations may continue to show requirements that have since been replaced.
Replacement of Net Worth with a Deposit Requirement
The SEBI (Investment Advisers) (Second Amendment) Regulations, 2024, effective from 16 December 2024, substituted the earlier Regulation 8 with a deposit requirement. Investment Advisers must now maintain the amount specified by SEBI through the prescribed arrangement.
The change means that current financial compliance centres on an identified deposit rather than demonstrating the former minimum net worth threshold. The amount is linked to the adviser’s client count under the applicable. Applicants should consequently avoid arranging capital or obtaining certificates solely on the assumption that the historical ₹5 lakh or ₹50 lakh thresholds remain compulsory. They should first identify the current deposit requirement and the procedure for satisfying it.
Understanding Net Worth
General Meaning of Net Worth
In general accounting terms, net worth represents the value remaining after liabilities are deducted from assets. It provides an indication of the financial position of an individual or business at a particular date. For example, if a business has assets of ₹25 lakh and liabilities of ₹10 lakh, the simple difference is ₹15 lakh.
However, a regulatory calculation may require adjustments to this figure. Certain assets or accounting items may be excluded or treated differently. Net worth is also capable of changing over time. Profits may increase it, while losses may reduce it. A substantial initial investment does not necessarily mean that the business continues to have the same financial strength several years later.
Regulatory Meaning of Net Worth
A regulatory definition determines which items can be counted and what adjustments must be made. It may address paid-up capital, reserves, accumulated losses, intangible items and expenditure that has not been written off. This is why a general statement that a founder owns property or has substantial savings does not automatically establish compliance with a particular regulatory financial requirement.
The relevant rule determines how financial evidence must be assessed. Under the current Investment Adviser, personal or business wealth should not be confused with the prescribed deposit. An adviser with substantial assets must still establish the required deposit and lien arrangement.
Earlier Requirements for Individual Investment Advisers
Under the former Regulation 8, individual Investment Advisers were required to maintain net tangible assets of at least ₹5 lakh. This was a historical financial eligibility condition applicable under the earlier. The term “net tangible assets” should not be confused with annual income, turnover or the total market value of everything owned by an individual. It concerned the financial position assessed under the applicable requirement.
Today, the ₹5 lakh figure should not be described as the current minimum deposit for an individual adviser. An applicant finding this threshold in an older article should check the date and regulatory version before relying on it. Understanding the historical requirement is useful when reviewing earlier filings or compliance records. It is less useful as a basis for estimating the current cost of entering the profession.
Earlier Requirements for Non-Individual Investment Advisers
The former required non-individual Investment Advisers to maintain net worth of at least ₹50 lakh. The calculation involved specified adjustments to capital, reserves, losses and other accounting items. Even under that, ₹50 lakh in net worth was not identical to ₹50 lakh in paid-up share capital. A company’s capital contribution was only one part of the assessment.
For example, a company could have substantial paid-up capital but also significant accumulated losses. Its net worth would therefore require a broader calculation than simply reading the share capital figure. The historical threshold should not now be presented as a compulsory ₹50 lakh capital contribution for every company or LLP proposing to obtain Investment Adviser registration.
Current Deposit Requirements
Deposit Linked to Client Numbers
The current links the deposit to the maximum number of clients on any day of the previous financial year. The prescribed amount is ₹1 lakh for up to 150 clients, ₹2 lakh for 151 to 300 clients, ₹5 lakh for 301 to 1,000 clients and ₹10 lakh for 1,001 clients or more.
This creates a financial requirement that changes with the scale of the advisory practice. A business should therefore monitor its client count and maintain records supporting the applicable slab. The deposit should be considered separately from the funds needed to establish and operate the business. Maintaining it does not, by itself, demonstrate that the adviser can meet staffing, technology and other recurring expenses.
Maximum Client Count Rather Than Only Year-End Count
The prescribed basis refers to the maximum client count on any day of the previous financial year. Consequently, the number recorded on 31 March alone may not establish the correct deposit amount.
Suppose a practice had 230 clients at its highest point during the year but only 140 at year-end. The calculation cannot simply ignore the higher count. Applying the stated slab basis would place the practice in the 151–300 category. This makes accurate onboarding and closure records important. A business should be able to explain how it arrived at the client count used for its deposit review.
Annual Revision of the Deposit
Where the applicable amount changes based on the previous financial year’s maximum client count, the revision must be completed by 30 April of the subsequent financial year. The review should therefore be included in the adviser’s compliance calendar. It should not depend on someone noticing the requirement after the deadline.
Planning ahead is especially useful for a growing business. Finance and compliance personnel can review the likely slab, arrange funds and complete the necessary documentation in a coordinated manner.
Initial Deposit for Fresh Applicants
A fresh applicant may not have a previous financial year’s advisory client history. Such an applicant should follow the initial-deposit instructions applicable through the registration process. The absence of historical clients should not be interpreted as an exemption from the deposit requirement. Applicants should confirm the prescribed arrangement before finalising their funding plan.
A business anticipating rapid growth should also budget for future increases. This avoids using all available funds for launch expenses and then facing difficulty when additional restricted funds are needed.
Permitted Forms of Deposit
Deposit with a Scheduled Bank
A permitted bank deposit must follow the applicable procedure and carry the required lien in favour of the Investment Adviser Administration and Supervisory Body, commonly called the IAASB.
Simply keeping an equivalent balance in a business account is not the same as establishing the prescribed arrangement. The deposit instrument, lien confirmation and supporting records must accurately reflect the requirement. Applicants should coordinate with the institution and supervisory body when arranging the deposit. Clear documentation reduces the possibility of a mismatch between the account holder, registrant and lien details.
Liquid Mutual Fund Units
SEBI permits eligible liquid mutual fund units to be used for compliance with the deposit requirement, subject to prescribed conditions. This provides an alternative to the permitted bank deposit route. However, the permission concerns eligible instruments and the required arrangement. It should not be extended to every mutual fund or investment that appears liquid.
An applicant considering this option should confirm the eligible category, documentation and lien process. The decision should account for compliance administration as well as the business’s financial planning.
Overnight Mutual Fund Units
Eligible overnight mutual fund units are another permitted option under the applicable. These units must also be maintained through the prescribed conditions and lien arrangement.
The availability of an alternative instrument does not remove the restriction over the amount. The funds should not be treated as freely available for business expenditure merely because the underlying investment can ordinarily be redeemed. Any change of instrument must be managed through the applicable procedure to avoid a gap in compliance.
Meaning and Purpose of the Lien
Restriction Over the Identified Funds
A lien places a restriction over the identified deposit or units in favour of the designated body. The adviser should therefore regard the amount as subject to regulatory conditions. This matters when preparing cash-flow forecasts. Funds carrying the lien should not be counted as money available for rent, salaries, marketing or other routine expenditure.
If the business needs to replace or alter the deposit arrangement, it should follow the prescribed procedure. An internal decision to move the funds does not independently authorise their release.
Availability for Specified Dispute-Resolution Dues
The amended Regulation 8 provides for utilisation of the deposit where an adviser fails to pay dues arising from specified arbitration or conciliation proceedings under the applicable dispute-resolution mechanism.
The deposit should not be represented as insurance against investment losses. It does not guarantee the performance of securities or eliminate market risk. Its existence is also not a substitute for responsible advice, proper documentation or effective complaint handling. Those remain separate elements of operating an advisory practice.
Difference Between Net Worth, Capital, Deposit and Working Funds
Net Worth
Net worth describes the financial position of a person or entity under the relevant calculation. It may change with profits, losses and adjustments to assets or liabilities. A founder should therefore avoid treating a historical contribution as proof of current financial strength. The position at the relevant date must be examined.
Paid-Up Capital or Capital Contribution
Paid-up capital represents contributions to a company’s share capital. LLPs and partnership firms have their own contribution arrangements. These contributions support the entity’s ownership and funding structure. They are different from the identified regulatory deposit, even where contributed funds are subsequently used to establish that deposit. The internal accounts should make the source and use of funds clear. This helps the business distinguish ownership funding from restricted amounts and operating expenditure.
Regulatory Deposit
The regulatory deposit is maintained through a prescribed instrument and lien. Compliance depends on the applicable amount and arrangement. A company may have a high net worth but still need to establish the deposit separately. Likewise, a business maintaining the deposit may have limited unrestricted cash. The deposit should therefore be assessed as one financial compliance requirement within a broader business plan.
Operating Funds
Operating funds support routine expenditure. These may cover personnel, premises, technology, accounting, professional support and other costs. For example, a founder with an initial budget of ₹5 lakh should distinguish the portion committed to the deposit from the amount available for operations. Otherwise, the business may appear better funded than it actually is.
Deposit and Registration Fees
Registration-related payments and the deposit serve different purposes. Application charges, registration fees and supervisory charges are payments associated with the regulatory process or supervision. The deposit follows a separate arrangement. Applicants should therefore avoid describing the deposit as a government fee or combining all financial requirements into one unexplained amount.
A clear budget should identify certification expenses, registration-related payments, the deposit, professional assistance and operating costs separately. This allows the founder to understand which amounts are expenses and which remain subject to restriction.
Financial Planning for Different Business Structures
Individual Advisers and Sole Proprietors
Individual practitioners should distinguish personal finances from the funds committed to the advisory business. Household expenses, emergency savings and business funding may all place demands on the same founder. A realistic plan should account for both the prescribed deposit and the period needed to build a stable practice. The founder should consider how recurring expenses will be met if client acquisition is slower than expected.
Companies, LLPs and Partnership Firms
Entities should establish a clear funding plan showing capital contributions, restricted funds and operating balances. Responsibility for managing each should be assigned. Where several owners are involved, the contribution arrangements should also address how additional funds will be provided if the deposit slab or operating expenses increase. Addressing this early can prevent disputes later.
Part-Time Advisers
Part-time registration should not be assumed to remove financial compliance obligations. Applicants must meet the requirements applicable to their category. A professional considering this route should review the permitted scale of the practice and its anticipated costs. Even a smaller advisory activity needs reliable records and sufficient resources to maintain its obligations.
Practical Examples
-
A Practice with 120 Clients: Assume a practice recorded a maximum of 120 clients during the relevant previous financial year. Under the stated slabs, the corresponding deposit is ₹1 lakh. The adviser should retain evidence supporting the client count and ensure that the amount is maintained through the prescribed arrangement. Identifying the correct slab is only one part of compliance.
-
A Practice with a Lower Year-End Count: Assume a practice reached 240 clients during the year but finished with 145 clients. Applying the maximum-client-count basis places it in the 151–300 slab, corresponding to ₹2 lakh. This example demonstrates why a year-end total can be misleading. A record of changes throughout the year supports a more accurate assessment.
-
An Entity with 850 Clients: Assume a non-individual adviser recorded a maximum of 850 clients during the relevant year. The corresponding deposit is ₹5 lakh. The entity should separately consider the resources needed to serve those clients. Staff, systems and review procedures may require substantially more funding than the deposit alone.
Whether a Net Worth Certificate Is Still Required
A certificate intended solely to demonstrate the former IA net worth threshold should not automatically be treated as a current compulsory document under the replaced provision. However, financial statements or certificates may still be requested for another regulated activity, a banking arrangement or a specific assessment. The purpose and basis of the request should be identified.
Applicants should use the current checklist and respond accurately to relevant queries. Replacing the IA threshold does not mean that all financial information becomes irrelevant.
Documentation and Internal Controls
-
Deposit and Lien Records: The compliance file should contain the deposit instrument, lien confirmation, relevant correspondence and evidence of authorised changes. Keeping these documents together makes it easier to demonstrate compliance and manage replacement or release procedures. Records should remain consistent with the registrant’s identity and current business arrangements.
-
Client Count Records: Client records should support the applicable maximum count and annual review. The method used should be consistent with the governing instructions. Where uncertainty exists about the treatment of a particular arrangement, the adviser should obtain the relevant clarification rather than use an unsupported assumption.
-
Responsibility for Review: Responsibility should be assigned for checking the deposit amount, arranging funds and completing procedural steps. In a larger entity, finance and compliance teams may share the work. A smaller practice may have one person performing these functions, but the review should still be documented. Clear responsibility helps ensure that the requirement is not overlooked.
Withdrawal, Reduction and Release
An adviser should not withdraw or reduce a deposit informally. Changes must follow the applicable supervisory procedure, including where the client count falls or the adviser wishes to use another permitted instrument. Similarly, an intention to close the business does not make the funds immediately available. Applicable surrender, closure and release procedures must be completed. Planning these changes carefully helps avoid releasing an existing arrangement before the replacement or required approval is in place.
Financial Sustainability Beyond Compliance
The removal of the older threshold does not eliminate the practical need for a financially stable business. An adviser may meet the deposit requirement but still lack sufficient funds to operate consistently. A cash-flow forecast should consider realistic client acquisition, fee receipts and recurring expenditure. It should also allow for unexpected costs.
For example, a business that spends most of its available funds on launch activities may struggle to maintain systems or staff before revenue becomes predictable. Regulatory compliance and financial sustainability should therefore be planned together.
Common Mistakes to Avoid
One common mistake is presenting the historical ₹5 lakh requirement for individual Investment Advisers and ₹50 lakh requirement for non-individual advisers as current eligibility conditions. These thresholds have been replaced by the prescribed deposit. Applicants also confuse the deposit with paid-up capital, working capital or registration fees, although each serves a different purpose. Another error is relying exclusively on year-end client numbers instead of examining the maximum client count during the relevant previous financial year. This can lead to an incorrect deposit calculation and subsequent compliance difficulties.
Advisers may also assume that any readily redeemable investment qualifies, overlook the prescribed lien or miss the annual deposit review. These errors can be reduced by checking current regulatory instructions, maintaining reliable client records and preserving deposit documentation. Assigning responsibility for monitoring deadlines, verifying the applicable slab and coordinating authorised changes helps ensure that financial compliance remains consistent as the practice grows.
Conclusion
The financial requirements for Investment Advisers in India have evolved from minimum net worth thresholds to a prescribed deposit linked to client numbers. Understanding this change is essential for applicants preparing registration documents and existing advisers reviewing compliance. The former ₹5 lakh and ₹50 lakh thresholds should be explained as historical requirements. Current compliance requires identifying the applicable deposit amount, maintaining it through an eligible instrument and establishing the prescribed lien arrangement. Following outdated guidance can result in unnecessary funding decisions or incomplete compliance arrangements.
Advisers should distinguish the regulatory deposit from capital contributions, registration charges and operating funds. Accurate client records, timely reviews and organised documentation help demonstrate compliance and support adjustments when required. However, maintaining the deposit alone does not establish financial sustainability. A realistic funding plan should also cover staffing, technology and continuing compliance expenses, enabling the business to deliver consistent services while meeting regulatory obligations.
Frequently Asked Questions (FAQ’s)
Q1. Is minimum net worth still required for SEBI Investment Adviser registration?
Ans. The earlier minimum net worth requirements have been replaced with a mandatory deposit requirement. Applicants must follow the current deposit rather than rely on the historical ₹5 lakh and ₹50 lakh thresholds. Other regulated activities may have separate financial requirements.
Q2. What were the earlier financial requirements?
Ans. Under the former, individual Investment Advisers needed net tangible assets of at least ₹5 lakh. Non-individual Investment Advisers needed net worth of at least ₹50 lakh. These are historical thresholds and should not be presented as current IA eligibility conditions.
Q3. When was the net worth requirement replaced?
Ans. The SEBI (Investment Advisers) (Second Amendment) Regulations, 2024, effective from 16 December 2024, replaced the earlier Regulation 8 with a deposit requirement. Subsequent directions specify the deposit amounts and permitted arrangements.
Q4. What deposit must an Investment Adviser maintain?
Ans. The prescribed deposit is ₹1 lakh for up to 150 clients, ₹2 lakh for 151–300 clients, ₹5 lakh for 301–1,000 clients and ₹10 lakh for 1,001 clients or more. The slabs are based on the maximum client count on any day of the previous financial year.
Q5. Is the deposit calculated using only year-end client numbers?
Ans. No. The prescribed basis is the maximum number of clients on any day of the previous financial year. For example, a practice that reached 220 clients but ended the year with 140 falls within the 151–300 slab for that calculation.
Q6. When must the deposit amount be revised?
Ans. An applicable revision based on the previous financial year’s maximum client count must be completed by 30 April of the subsequent financial year. Advisers should maintain accurate records and include this review in their compliance calendar.
Q7. Can the deposit be maintained in mutual fund units?
Ans. Yes. Eligible liquid and overnight mutual fund units are permitted, subject to prescribed conditions and lien arrangements. This permission does not extend automatically to equity funds, other mutual fund categories or any investment considered easy to sell.
Q8. What does marking a lien over the deposit mean?
Ans. A lien places a restriction over the identified deposit or units in favour of the designated supervisory body. The adviser cannot treat the amount as unrestricted business funds. Withdrawal, replacement or release must follow the applicable procedure.
Q9. Is the deposit the same as a registration fee?
Ans. No. Registration fees and supervisory charges are separate payments. The deposit is maintained through a prescribed arrangement and remains subject to the required lien. Applicants should budget for these components separately.
Q10. Can an adviser use the deposit for salaries or rent?
Ans. The deposit should not be treated as freely available working capital. Routine expenses must be funded separately. Any release or alteration of the deposit must follow the applicable supervisory requirements.
- 12 Oct, 2026
 CA Manish Mishra
- Easing Finance
CA Manish Mishra is the Co-Founder & CEO at GenZCFO. He is the most sought professional for providing virtual CFO services to startups and established businesses across diverse sectors, such as retail, manufacturing, food, and financial services with over 20 years of experience including strategic financial planning, regulatory compliance, fundraising and M&A.